Listen to the summary
Key Data Snapshot
| Metric | Value | Note |
|---|---|---|
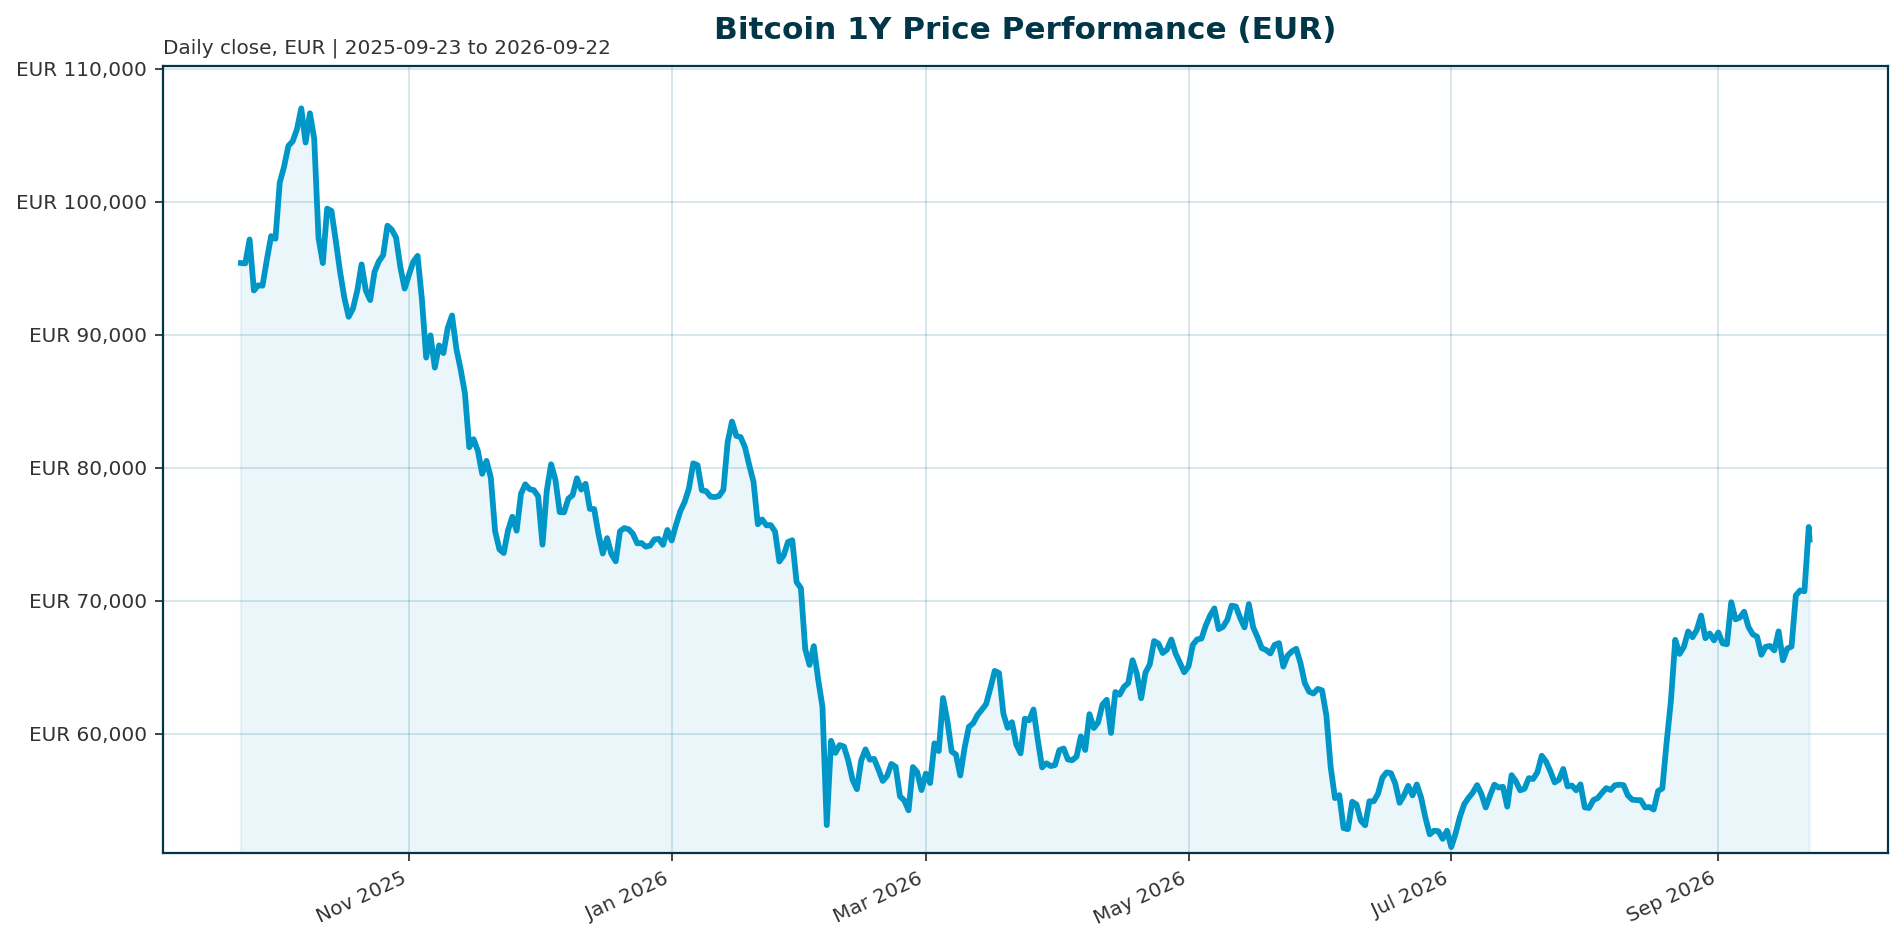
| Price (EUR) | 74,641 | 24h range 70,858 to 76,118 (~7.42% band: (76,118 − 70,858) / 70,858) |
| Market cap | EUR 1.499trn | Rank #1; +EUR 76.4bn (+5.37%) over 24h |
| Fully diluted valuation | EUR 1.499trn | Equals market cap; 95.66% of max supply issued (20,087,715 / 21,000,000) |
| Volume 24h | EUR 53.49bn | Turnover ~3.57% of market cap (53.49 / 1,499.4) |
| Change 24h / 1h | +5.39% / -0.12% | Intraday consolidation after strong move |
| Change 7d / 14d / 30d | +9.92% / +8.46% / +11.09% | Consistent recovery momentum |
| Change 200d / 1y | +20.18% / -25.08% | ~36pp spread between 30d and 1y: recovery phase after a deep drawdown |
| ATH | EUR 107,662 (2025-10-06) | Current price -30.67% below ATH |
| BTC dominance | 58.80% | Total crypto market cap EUR 2.543trn; total crypto volume 24h EUR 138.56bn |
| Implied USD price | ~USD 85,675 | Approximation: 74,641 x 1.1484 (EUR/USD) |
Performance framing: the asset is in a post-correction recovery. The 30-day gain of +11.09% contrasts with a -25.08% one-year return and a Q4 2025 episode in which more than USD 1trn in market value was erased as price fell nearly 30% from its peak [T2].
Market Setup
Cross-asset context: risk sentiment is neutral to positive and equity momentum is mixed. The Nasdaq Composite leads the 5-day board at +4.39%, while the DAX is the weakest at +0.68%; DACH indicators average +1.48% over 5 days versus +2.68% for global equities, a 1.2pp lag that signals softer European risk appetite. The rates backdrop is mixed: the euro-area AAA 10Y yield sits at 3.53% (-1.1bp over 5 days) and the 10Y-2Y spread at 31.5bp, but the curve has shifted sharply higher over the past month (2Y +43.4bp, 10Y +25.2bp), keeping the opportunity cost of a non-yielding asset elevated. FX is mixed: EUR/USD at 1.1484 (-0.08% 5d, -2.28% YTD) means EUR-denominated returns diverge from USD returns; EUR/JPY shows the strongest 5-day FX move at +0.32%. This backdrop is contextual and secondary to Bitcoin-specific flow dynamics.
Bitcoin-relevant macro read-through: under Fed Chair Kevin Warsh, the central bank is expected to hold rates through Q3 2026, leaving limited room for the easing that has historically supported risk-asset recoveries [T1]. Separately, surging US Treasury yields have been cited as a clear headwind, as higher yields raise the opportunity cost of holding a volatile, non-yielding asset and make institutional buyers more selective [T4].
Investment Thesis
Bitcoin now trades in an ETF- and macro-led regime. Regulated capital flows, not retail speculation, are the marginal price setter. Record outflows from US-listed BTC and ETH ETFs in Q4 2025 coincided with the break of USD 98,000 support and a retest of the low USD 90,000 range, demonstrating how tightly price action tracks regulated flows [T2]. Kraken’s 2026 outlook frames the shift as one from hype to structure: spot ETFs and digital asset treasury companies now shape price discovery, even as headline gains have lagged the scale of inflows [T6].
The demand channel has re-engaged. Weekly BTC ETF inflows surged to USD 1.92bn in late August 2026, with BlackRock’s IBIT taking a significant share, and positioning appears anticipatory rather than reactive given still-low broad-market volumes [T8]. Earlier in the year, inflows of roughly USD 467mn on May 5 marked the fourth consecutive positive day [T7]. On the supply side, 6.7 million BTC sat across ETFs, exchanges, and treasuries at end-2025, which Glassnode described as Bitcoin’s “institutional supply era” [T2], against a hard cap of 21 million with 95.66% of coins already issued.
Balance: the thesis is flow-dependent. If inflows continue for several weeks, they provide structural support for rallies, especially when futures-driven liquidity is weak; if flows stall, the market needs another catalyst [T5]. Treasury firms may also face a tougher path issuing equity as premiums compress, limiting a previously powerful demand impulse without a clear risk-on backdrop [T6].
Bullish Drivers
Regulatory pipeline. The US CLARITY Act would establish a federal market-structure framework for digital assets and could unlock broader institutional participation if passed [T1]. The GENIUS Act and broader market-structure reform momentum, alongside stablecoin liquidity at all-time highs, form additional structural pillars [T6]. In Asia, Hong Kong’s Stablecoins Ordinance mandates full reserve backing, redemption rights, and risk controls, and institutional adoption is shifting from pilots to targeted deployment via tokenization [T1].
Institutionalization. Bitcoin’s volatility declined from 84% to 43% per the Glassnode x Fasanara 2025 report, supporting its evolution into a portfolio-allocatable line item for RIAs, private banks, and institutions [T2]. Daily ETF inflows have at times consistently exceeded USD 400mn, and analytics platforms publish 2026 forecast ranges of USD 85,000 to 132,000, with some institutional paths toward USD 150,000 contingent on regulation and adoption [T3].
Supply and flow persistence. The 21 million cap is unchanged, 95.66% of supply is issued, and remaining dilution is limited to mining issuance. Corporate treasuries increasingly treat BTC as a strategic reserve asset [T3]. Product innovation, including covered-call crypto ETFs, multi-asset index products, and institutional model portfolios, deepens the flow channel, and clarity in custody, market structure, and tax treatment could widen sideline participation [T5].
Relative Positioning vs Gold and Ethereum
Vs gold: the 2025 correction was a reminder that BTC remains a high-beta corner of global markets, lagging traditional assets like gold and bonds during the drawdown [T2]. Gold retains the safe-haven allocation edge in restrictive-rate environments. The bull case for relative positioning rests on flow concentration: if regulated demand keeps centering on BTC (the IBIT dominance pattern [T8]), BTC can narrow the gap with gold as a portfolio diversifier, while a repeat of 2025 would see it lag again.
Vs Ethereum: the two assets share the ETF flow channel and show correlated flow sensitivity; record outflows hit both BTC and ETH ETFs in Q4 2025 [T2], and inflows have rebounded together since [T5]. BTC dominance at 58.80% of the EUR 2.543trn crypto market confirms it retains the dominant share of crypto risk budgets. Regional nuance: in Asia, pure bitcoin ETF products play a smaller strategic role than in North America and Europe, where tokenization and stablecoins dominate institutional entry points [T1].
Limitation: this bundle contains no hard gold or ETH price data; the comparison above relies on qualitative source statements and dominance figures. Specific benchmark quotes are unavailable.
Scenario Framework
Bull case. The CLARITY Act passes and ETF inflows sustain after the US Treasury bond buyback program begins in September, which has been flagged as the likely determinant of the next leg [T8]. BTC reclaims former support zones and pushes toward the upper institutional forecast range of USD 120,000 to 150,000, roughly EUR 104,500 to 130,600 at EUR/USD 1.1484. Contingent, not a forecast [T1][T3].
Base case. The Fed holds through Q3 under Warsh [T1]; flows stay positive but decelerate, echoing the 2025 slowdown versus 2024 [T6]. BTC ranges between reclaimed USD 80,000 support and the USD 85,000 to 90,000 resistance zone [T7], with the USD 98,000 former support as the key breakout level [T2]. In EUR, the current price of 74,641 already implies ~USD 85,700, sitting at the lower bound of analytics-platform forecast ranges converted at EUR/USD 1.1484 (USD 85,000 to 132,000 equals roughly EUR 74,000 to 115,000) [T3]. EUR returns oscillate with the exchange rate.
Bear case. Flows stall or reverse in the Q4 2025 pattern, yields surge further and raise the opportunity cost of holding BTC [T4], and treasury-firm premium compression removes a demand channel [T6]. BTC retests lower support bands and underperforms gold again [T2]. A single week of record outflows can break key support rapidly given flow-dominated price discovery.
Valuation Discussion
Scarcity framing. FDV equals market cap at EUR 1.499trn because 95.66% of the 21 million cap is in circulation; issuance-driven dilution is nearly exhausted, and supply growth is limited to residual mining rewards. Cross-check: 74,641 x 20,087,715 gives ~EUR 1.4997trn versus the reported 1.4994trn, a rounding-level discrepancy.
Flow-based framing. ETF flows are the marginal price setter. Weekly inflows of USD 1.92bn against relatively low broad-market trading volumes signal anticipatory institutional positioning rather than reactive chasing [T8]. Valuation therefore hinges on flow persistence, not on classic halving-cycle reflexivity; Kraken argues the cycle is increasingly shaped by institutional plumbing rather than halving mechanics [T6], while more bullish commentary treats the 2024 halving cycle as still in effect [T3].
FX-adjusted levels. USD forecast ranges of 85,000 to 132,000 translate to roughly EUR 74,026 to 114,943 at EUR/USD 1.1484; the USD 150,000 upper path equals ~EUR 130,615 [T3]. The current EUR price of 74,641 sits at the bottom of the converted range. EUR-denominated returns diverge from USD returns: EUR/USD is down 2.28% YTD, and further EUR appreciation would erode EUR returns.
Valuation scenarios. Expansion: if BTC re-rates as a lower-volatility institutional allocation (vol 43% per the 2025 report [T2], date-stamped and possibly stale), multiples anchored to flow persistence justify the upper band. Compression: if ETF flows prove cyclical, valuation reverts to high-beta risk-asset framing and the 2025 pattern of lagging gold and bonds recurs.
Risks
Flow reversal. The Q4 2025 precedent is explicit: record ETF outflows broke USD 98,000 support and over USD 1trn in market value was erased as BTC fell nearly 30% from its peak [T2]. Flow-dominated price discovery cuts both ways.
Concentration. IBIT’s outsized share of recent inflows creates single-product concentration risk; a pullback by one dominant fund could remove disproportionate marginal demand [T8].
Restrictive rates. Rising US Treasury yields raise the opportunity cost of a volatile, non-yielding asset and make institutional buyers more selective [T4]; no Fed easing is expected through Q3 2026 [T1].
Regulatory and reflexivity risk. The CLARITY Act benefit is conditional on passage; failure or delay removes the primary identified catalyst [T1]. Kraken cautions that ETF inflows slowed in 2025 versus 2024 and that treasury firms’ equity issuance becomes harder as premiums compress, limiting reflexive demand [T6].
Liquidity. Volume-to-market-cap turnover of ~3.57% and still-relatively-low broad crypto volumes mean large outflows would meet thin spot liquidity [T8].
FX and regional. EUR/USD at 1.1484 (-2.28% YTD): EUR appreciation erodes EUR-denominated returns. DACH equities lagging global peers (+1.48% vs +2.68% over 5 days) points to weaker European risk appetite, which is relevant for altii’s EUR-based reader base.
Appendix
Methodology and provenance. Market data retrieved 2026-09-22 04:15 UTC via CoinGecko with EUR as quote currency; all prices and performance figures are EUR-denominated unless noted. Macro data as-of dates: equities 2026-09-21 (Nikkei 2026-09-18), ECB AAA yield curve 2026-09-18, FX 2026-09-22. USD-denominated levels from news sources are converted at EUR/USD 1.1484 (2026-09-22, Frankfurter FX) and labeled as approximations. News sources span January 2026 (Kraken outlook) to August 2026 (ETF inflow data); several lack publication dates, and readers should treat undated flow and forecast figures accordingly. The volatility figure of 43% originates from a 2025 report and may not reflect September 2026 conditions. Benchmark comparison vs gold and ETH relies on qualitative source statements because no hard benchmark quotes were included in this data bundle; specific gold and ETH prices are unavailable. The 6.7 million BTC institutional-holding figure is from end-2025 and likely stale. ETF flow figures from different dates (May 5: USD 467mn; late August weekly: USD 1.92bn) are presented as a flow-regime time series and are not aggregated.
Calculations shown. Supply issued: 20,087,715 / 21,000,000 = 95.66%. Turnover: 53,490,702,494 / 1,499,425,504,135 = 3.57%. Intraday band: (76,118 − 70,858) / 70,858 = 7.42%. Implied USD price: 74,641 x 1.1484 = ~USD 85,675. Forecast range conversion: 85,000 / 1.1484 = ~EUR 74,026; 132,000 / 1.1484 = ~EUR 114,943; 150,000 / 1.1484 = ~EUR 130,615. ATH distance: 74,641 / 107,662 − 1 = -30.67%.
Sources
- [T1] Q2 2026 Digital Asset Review, CoinDesk Indices: link
- [T2] Crypto Market 2025: Year-End Review & Expert Insights, TradingView/99Bitcoins: link
- [T3] Bitcoin Price Prediction 2026: Institutional Adoption, Intellectia: link
- [T4] US Treasury yields surge to new highs as liquidity tightens, CryptoSlate: link
- [T5] Bitcoin and Ether ETF Inflows Rebound, Blockchain Council: link
- [T6] Kraken sees 2026 crypto markets shifting from hype to structure, The Block: link
- [T7] Bitcoin Price Analysis May 2026, Intellectia: link
- [T8] Bitcoin ETF Inflows Surge to $1.92 Billion Last Week, Cryptonomist: link
Disclaimer. This report is AI-generated and for informational purposes only. It does not constitute investment advice, a recommendation, or an offer to buy or sell any security or asset. Scenarios and price ranges are analytical constructs, not forecasts. Data may contain errors or staleness; readers should verify independently before making decisions.
Important Note / Wichtiger Hinweis:
EN: This report may have been generated using AI. It processes data from publicly available sources. The content is provided for informational purposes only.DE: Dieser Bericht kann mithilfe von KI erstellt worden sein. Dabei werden Daten aus öffentlich zugänglichen Quellen verarbeitet. Die Inhalte dienen ausschließlich Informationszwecken.
* DE: Die ergänzenden Inhalte können KI-generiert sein. EN: The additional content may be AI-generated.