Watch the video
The altii daily market briefing presents Market Overview, Gold and Bitcoin as a video with charts and audio commentary.
▶ Watch the daily videos on tube.altii.de
Key Data Snapshot
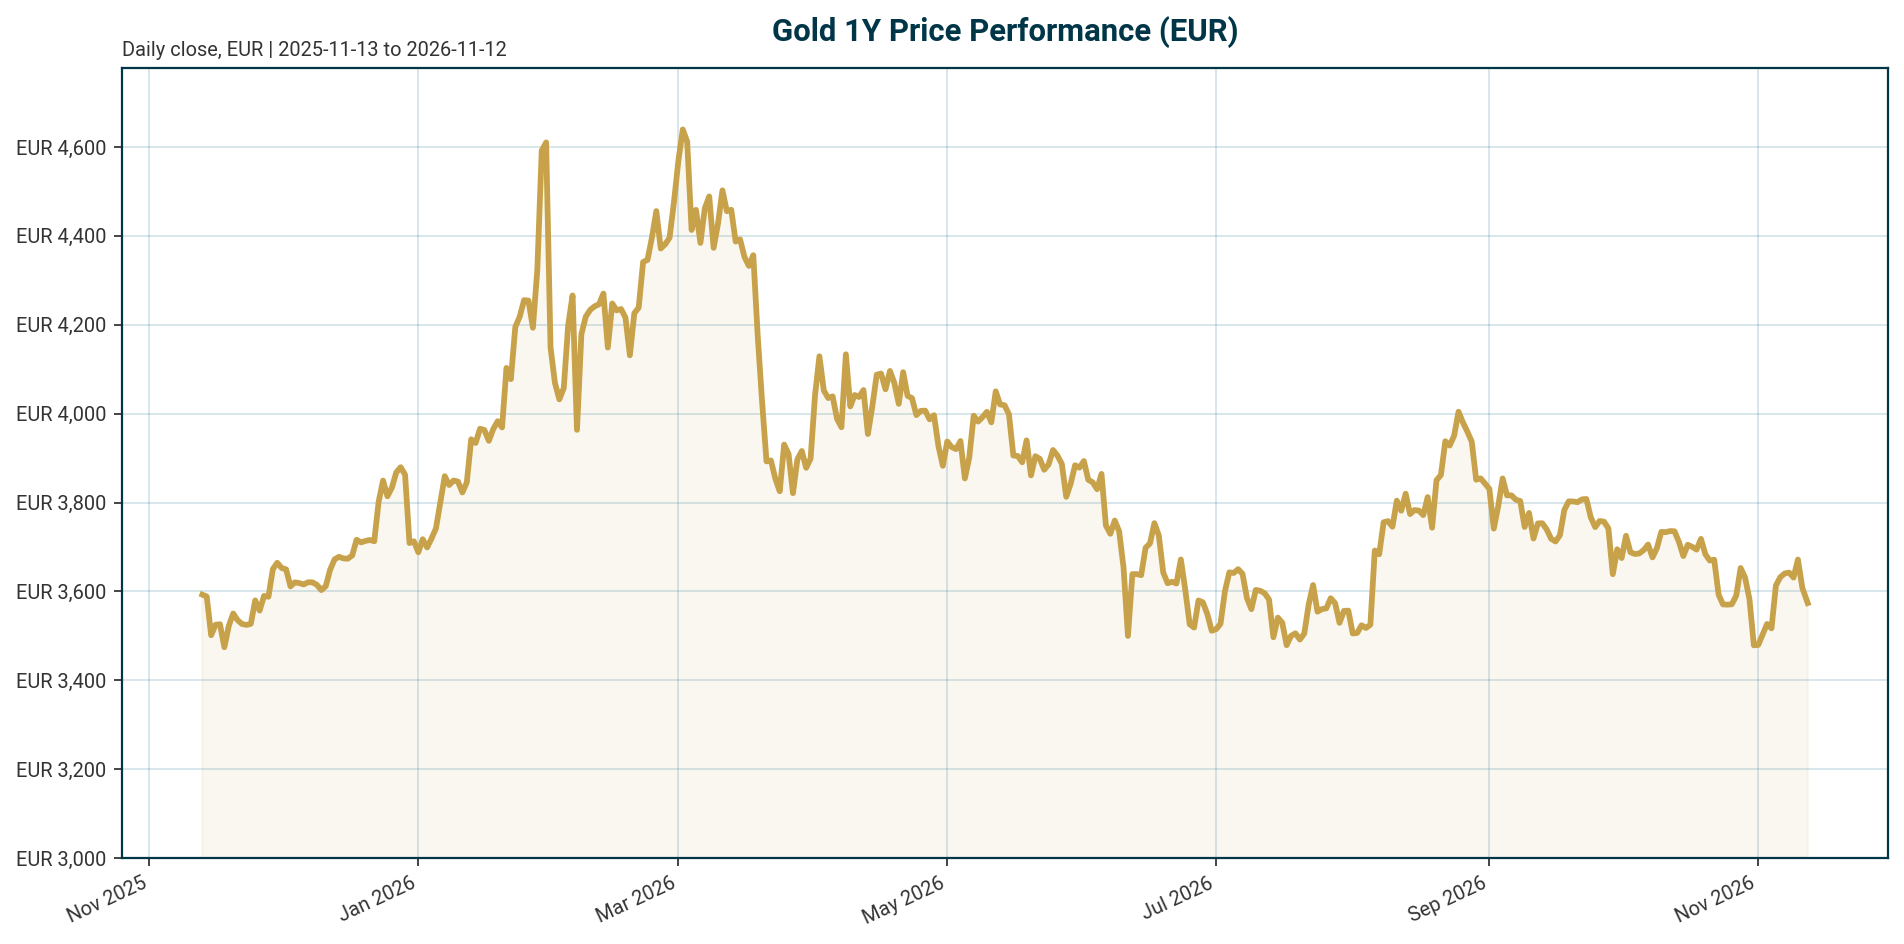
Gold (XAU) quoted in euro trades at 3,579.22 EUR as of 12 November 2026, down 1.19% over 24 hours and 3.92% over seven days. The metal sits 23.66% below its all-time high of 4,688.32 EUR set on 28 January 2026, but remains 182.88% above its 2019 low of 1,265.28 EUR. Market cap and volume figures below reflect the PAX Gold token wrapper that tracks XAU, not the full physical gold market.
| Metric | Value |
|---|---|
| Price (XAU/EUR) | 3,579.22 EUR |
| 24h range | 3,577.33 to 3,656.75 EUR |
| 24h / 7d / 14d change | -1.19% / -3.92% / -1.70% |
| 30d / 200d / 1y change | -5.24% / -15.43% / -3.31% |
| All-time high | 4,688.32 EUR (2026-01-28); current price -23.66% |
| 24h volume (token) | 68.41m EUR |
| Fed funds target range | 3.75% to 4.00% (as of 2026-11-11); last change: hike of 25 bp, effective 2026-09-17 |
| ECB deposit facility rate | 2.50% (as of 2026-11-12); last change: hike of 25 bp, effective 2026-09-16 |
| Euro area AAA 10Y yield | 3.33% (+38.3 bp YTD, as of 2026-11-10) |
| Euro area AAA 10Y-2Y spread | 31.2 bp |
| EUR/USD | 1.1176 (-4.89% YTD) |
The momentum profile shows a second-half correction within a positive 12-month trend: the 200-day change of -15.43% contrasts with a 1-year change of only -3.31%, meaning most of the damage was done since roughly May 2026.
Macro Backdrop
Market overview: Risk sentiment is neutral to positive with moderately negative equity momentum. DACH indicators average +2.39% over five days versus +3.29% for global equity indicators, so the region broadly tracks the global picture. The Nikkei 225 posts the strongest five-day move at +6.31% while the Hang Seng is weakest at -1.49%; the DAX leads on a one-month basis at +5.48%. The rates backdrop is mixed: the euro area AAA 10Y yield stands at 3.33%, moving -0.9 bp over five days, with a 10Y-2Y spread of 31.2 bp. FX is similarly mixed, with EUR/USD at 1.1176 (-0.19% over five days) and EUR/CHF the strongest five-day mover at +0.75%. This backdrop is context only; the gold-specific analysis below dominates the assessment.
Policy: Both major central banks have tightened recently. The Fed funds target range is 3.75% to 4.00% after a 25 bp hike effective 17 September 2026, and the ECB deposit facility rate is 2.50% after a 25 bp hike effective 16 September 2026. Market pricing points further in the hawkish direction: traders see an 84% probability of a Fed rate hike in December according to CME’s FedWatch tool, per [T6] from November 2026. Richmond Fed President Barkin said policy should move “with care” and called inflation the central bank’s “greatest risk”, with no base case for December, per the same source.
Inflation: October US headline CPI rose 0.4% month on month against a 0.3% expectation, and core CPI rose 0.3% versus a 0.2% forecast, per [T8] from November 2026. Deutsche Bank strategists cited in that source note the three-month annualised core pace runs at +3.75%, the fastest since April 2024. Fed Governor Waller had signalled a possible half-point December hike if core inflation stayed around 0.3% or higher, per the same source. This is the central tension for gold: sticky inflation is normally bullish, but here it drives hawkish policy expectations that lift real yields, the primary cyclical headwind for non-yielding bullion.
For euro-based holders, the domestic yield curve matters directly. Euro area AAA 2Y yields are at 3.02% (+91 bp YTD) and the 10Y at 3.33% (+38 bp YTD), so the opportunity cost of holding gold in EUR terms has risen meaningfully this year.
Investment Thesis
The core thesis is a contest between a structural bid and a cyclical headwind. On the structural side, central bank demand has become a durable anchor of the gold market. Global official holdings grew by an average of 1.2% per year over 2009 to 2025, and DBS research describes central bank allocations as a “dominant structural anchor” driven by reserve optimisation in a fragmented geopolitical environment, per [T4] from November 2026. A record 43% of 73 surveyed monetary authorities expect their own gold reserves to increase over the next year, per [T2]. Gold’s ability to hold near historic highs despite fluctuating rate expectations reflects this structural rather than speculative bid, per [T1] from November 2026.
On the cyclical side, the hawkish repricing is real and quantified. With the Fed funds range at 3.75% to 4.00% after the September hike, and an 84% market-implied probability of a further December hike (per [T6], Nov 2026), real-yield pressure on gold persists into year-end. Higher rates raise the opportunity cost of holding non-yielding bullion, per [T6].
For EUR investors there is a third variable: currency. EUR/USD at 1.1176 is down 4.89% YTD, so euro depreciation has mechanically cushioned XAU/EUR relative to XAU/USD. The 1-year XAU/EUR change of -3.31% therefore likely overstates the USD-side weakness; part of the decline reflects a stronger dollar. The base case is rangebound-to-soft XAU/EUR while hawkish Fed expectations dominate, with official-sector and ETF flows providing a floor. The bullish offset is a growth-slowdown pivot: the World Gold Council’s scenario analysis suggests gold could rise 5% to 15% in 2026 if the Fed cuts beyond expectations, per [T5]. We treat that as a scenario assumption, not current pricing, especially since the same WGC outlook was written against a consensus of roughly 75 bp of additional Fed cuts, a path the recent inflation data has called into question.
Bullish Drivers
- Official-sector accumulation. Central bank gold holdings grew ~1.2% on average over 2009 to 2025, and DBS research calls this demand an increasingly durable source of structural support, per [T4] from November 2026. Gold is now viewed as a strategic reserve asset rather than a legacy holding.
- Reserve diversification and sanctions risk. Nations not allied with the United States are reducing dollar reserve mix to make reserves less vulnerable to sanctions, and others seek protection against higher and more volatile inflation, per [T2]. Concerns over US fiscal health, Fed independence and geopolitical instability reinforce this, per [T3] from September 2025.
- Investment channel growth. Surveyed institutions rank ETFs (27%), derivatives (27%) and tokenised gold (18%) as the channels with the strongest expected growth over the next 12 months, per [T4].
- ETF and investment flows. Continued central bank purchases and ETF inflows could provide longer-term support even as monetary policy expectations constrain the immediate recovery, per [T8] from November 2026.
- Dovish-pivot optionality. If a softer US labour market forces the Fed to cut beyond expectations, lower rates plus a weaker dollar and heightened risk aversion would create a supportive environment; the WGC scenario implies 5% to 15% upside in 2026, per [T5]. This is a scenario, not a current market expectation.
- Structural bid resilience. Gold held near record highs despite rising real yields in 2022 and 2023, posting a +13% return in 2023, evidence that the historical inverse real-yield relationship has broken down, per [T2].
One caution on sourcing: an ING piece [T7] cites China’s central bank buying 8.1 tonnes in April and holding roughly 2,305 tonnes across a 15-month streak. That source is undated and references April conditions, so we treat it as mechanism evidence only, not as a current holdings figure.
Relative Positioning vs Bitcoin and Ethereum
The bundle contains no current Bitcoin or Ethereum price series, so this comparison is necessarily qualitative on crypto returns. Context from the bundle: total crypto market cap stands at 2.22trn EUR with Bitcoin dominance at 59.88%, and the benchmark assets for this report are gold and ethereum.
The macro linkage runs through liquidity. Per [T1] from November 2026, a Bitcoin decline toward $60,000 would likely require a substantial macro catalyst such as a sharp rise in real yields, an aggressive hawkish Fed repricing, or a widespread liquidation event across equity and credit markets. These are precisely the catalysts that would pressure gold. The same source views $80,000 Bitcoin as more likely than $60,000 under current conditions, and notes investors continue to favour real and scarce assets amid restrictive liquidity, a shared tailwind for gold and hard assets.
The differentiation is beta and floor. Gold’s drawdown from its all-time high is -23.66% with a 1-year change of -3.31%, and its central-bank floor limits downside in a liquidity shock. Crypto assets typically carry higher beta to the same liquidity cycle, offering more upside in a dovish reflation but deeper drawdowns in a hawkish one. For EUR-based allocators seeking inflation and geopolitical hedging with lower drawdown risk, gold retains the defensive edge; for those seeking convexity to a dovish pivot, crypto offers higher torque. A convergence point worth monitoring: tokenised gold, which 18% of surveyed institutions expect to be among the fastest-growing investment channels, per [T4].
Scenario Framework
| Scenario | Key assumptions | XAU/EUR implication |
|---|---|---|
| Hawkish continuation (market-implied base case) | December Fed hike delivered (84% priced per [T6], Nov 2026), possibly 50 bp per the Waller signal ([T8], Nov 2026); core CPI stays near 0.3% MoM; real yields stay elevated. | Price stays under pressure near term. The $4,000 to $3,870 XAU/USD support zone described as decisive by FXStreet ([T8], Nov 2026) is the downside reference in USD terms; EUR conversion depends on EUR/USD, which is not a scenario variable we can fix from the dataset. |
| Status quo | Fed holds after December, inflation plateaus at elevated levels, euro yields rangebound (AAA 10Y near 3.33%). | Gold ranges. Central bank buying and ETF flows provide a floor while rate expectations cap rallies ([T4], [T8]). |
| Dovish pivot | Growth slowdown forces deeper easing than the pre-repricing consensus of ~75 bp of cuts ([T5]); dollar weakens; risk aversion rises. | WGC scenario analysis implies gold could rise 5% to 15% in 2026 from then-current levels ([T5]). Applied to the current XAU/EUR price of 3,579.22 and assuming an unchanged EUR/USD of 1.1176, that maps to roughly 3,758 to 4,116 EUR. The FX assumption is explicit and would change with the dollar path. |
Note the conflict between sources: the WGC outlook [T5] describes a consensus of additional Fed cuts, while the November 2026 market pricing in [T6] points to a hike. We treat the WGC consensus path as a dated, pre-repricing reference and the 84% December hike probability as the current market expectation.
Valuation Discussion
At 3,579.22 EUR, gold trades 23.66% below its January 2026 peak of 4,688.32 EUR and 182.88% above its 2019 low of 1,265.28 EUR. The calculation: (3,579.22 – 4,688.32) / 4,688.32 = -23.66%. This is a meaningful correction, not a collapse; the metal remains in a structurally elevated range.
Traditional valuation anchors are complicated by a broken relationship. Gold historically moves inversely to real yields, but that relationship has broken down over the past two years: despite real yields rising to post-2008 highs from 2022, gold was little changed in 2022 and posted +13% in 2023, per [T2]. The World Gold Council’s Gold Valuation Framework shows rangebound performance when consensus macro variables are input, per [T5], suggesting gold is broadly fair on consensus inputs rather than obviously cheap or rich.
The FX layer matters for EUR investors. EUR/USD at 1.1176 is down 4.89% YTD. As a rough decomposition, a 4.89% euro depreciation versus the dollar implies that a flat XAU/USD would translate into roughly +5% XAU/EUR appreciation (1 / 0.9511 – 1 = +5.1%). Against the actual 1-year XAU/EUR change of -3.31%, this implies the USD-side gold price has fallen meaningfully more than the EUR-quoted series, on the order of 8% on this proxy. The EUR-quoted investor has been partly insulated by currency.
On the opportunity-cost side, euro area AAA 10Y yields at 3.33% versus the ECB deposit rate of 2.50% mean euro investors can earn a positive real-adjacent carry on sovereign paper, a genuine competitive hurdle for zero-yield gold. The dataset contains no measured euro-area or US real-yield series, so real-yield direction is inferred from nominal moves and inflation persistence and should be read as a proxy only.
Balance of assessment: fair-to-slightly-rich on structural demand grounds given persistent official-sector buying, but with valuation risk skewed toward the lower end of the range if the hawkish path delivers a half-point December hike and the real-yield relationship re-asserts.
Risks
Downside risks:
- Hawkish Fed surprise. A half-point December hike is a live possibility per the Waller signal ([T8], Nov 2026), and traders price an 84% chance of some hike ([T6], Nov 2026). Higher rates raise the opportunity cost of non-yielding bullion and could extend the current 30-day drawdown of -5.24%.
- Sticky inflation. Core CPI running at a 3.75% annualised three-month pace ([T8], Nov 2026) keeps the Fed in tightening mode and supports the dollar, a double headwind for XAU in both USD and potentially EUR terms.
- Rising euro yields. Euro area AAA 10Y yields up 38 bp YTD at 3.33% raise the EUR-denominated opportunity cost specifically for the quote currency of this report.
- Safe-haven failure in supply shocks. Gold’s safe-haven appeal works best in financial crises or growth shocks; a supply-driven energy shock pushes inflation up, keeps central banks hawkish and strengthens the dollar, historically weighing on gold despite geopolitical stress. Gold’s high liquidity also makes it a source of funds in drawdowns, per [T7] (undated source, treat with caution).
- Fading geopolitical premium. Easing geopolitical tensions could reduce safe-haven demand, per [T8] from November 2026.
- Slowing official-sector demand. Central bank buying is already below the records of the previous three years, per [T5]. A further slowdown would remove the structural floor underpinning the bull case.
Upside risks:
- Fed independence and fiscal concerns. Worries over deteriorating US fiscal health, Fed independence and geopolitical instability could accelerate reserve diversification into gold, per [T3] from September 2025.
- Inflation downside surprise. A weaker-than-expected CPI print would invalidate the hawkish path and could trigger a rapid short-covering rally in gold.
- Growth shock. A labour-market deterioration would force the dovish-pivot scenario, with the WGC-implied 5% to 15% upside ([T5]) as the scenario reference.
Appendix
Data provenance. Bundle generated 2026-11-12T05:19:47Z; market data retrieved 2026-11-12T05:19:37Z. Policy rates are sourced exclusively from the bundle’s authoritative policy rates block: Fed funds target range 3.75% to 4.00% as of 2026-11-11 (FRED), ECB deposit facility rate 2.50% as of 2026-11-12 (ECB key rate). The ECB’s other key rates are not in the dataset and are therefore not stated. Euro-area yield curve data is as of 2026-11-10 (ECB yield curve); equity and FX data as of 2026-11-11 or 2026-11-12.
Source dating and caveats. News items lack published_at timestamps; dates are inferred from source URLs and content. [T6] and [T8] are from November 2026; [T3] is from September 2025; [T7] is undated and references April conditions, so it is used only for mechanism discussion, never for current levels. The WGC outlook [T5] reflects a consensus path of additional Fed cuts that predates the recent hawkish repricing and is labelled accordingly wherever used. Market cap (1.60bn EUR) and 24h volume figures reflect the PAX Gold token wrapper, not the physical gold market. No US real-yield series, 10Y Treasury yield, DXY level, or current BTC/ETH price series is present in the dataset; where such context matters, the report states it is unavailable or uses clearly labelled proxies.
Definitions. XAU/EUR is the gold price in euro per troy ounce as tracked by the bundle. “Market expectation” refers to probabilities implied by market pricing (CME FedWatch) and is distinct from central bank decisions, which are stated only from the policy rates block with their effective dates.
Sources
- [T1] Does $80,000 Bitcoin remain more likely than $60,000 as Gold and Oil signal persistent inflation risks? (FXStreet)
- [T2] Is it a golden era for gold? (J.P. Morgan Private Bank)
- [T3] COMMENTARY: Gold’s rise in central bank reserves appears unstoppable (Reuters, September 2025)
- [T4] Central banks are exploring Asian gold hubs for safe storage of reserves (Kitco News/DBS, November 2026)
- [T5] Gold Outlook 2026: Push ahead or pull back (World Gold Council)
- [T6] Gold edges lower as focus shifts to US inflation data (Reuters, November 2026)
- [T7] Why gold isn’t acting like a safe haven right now (ING THINK, undated)
- [T8] Gold is rebounding, but something is still pulling it back (FXStreet, November 2026)
Disclaimer: This report is AI-generated and for informational purposes only. It does not constitute investment advice, a recommendation, or an offer to buy or sell any financial instrument. Figures are drawn from the cited dataset and sources as of their retrieval dates and may be incomplete or stale. Readers should conduct their own research and consult a licensed advisor before making investment decisions.
Important Note / Wichtiger Hinweis:
EN: This report may have been generated using AI. It processes data from publicly available sources. The content is provided for informational purposes only.DE: Dieser Bericht kann mithilfe von KI erstellt worden sein. Dabei werden Daten aus öffentlich zugänglichen Quellen verarbeitet. Die Inhalte dienen ausschließlich Informationszwecken.