Watch the video
The altii daily market briefing presents Market Overview, Gold and Bitcoin as a video with charts and audio commentary.
▶ Watch the daily videos on tube.altii.de
Key Data Snapshot
| Metric | Value | Change / Context |
|---|---|---|
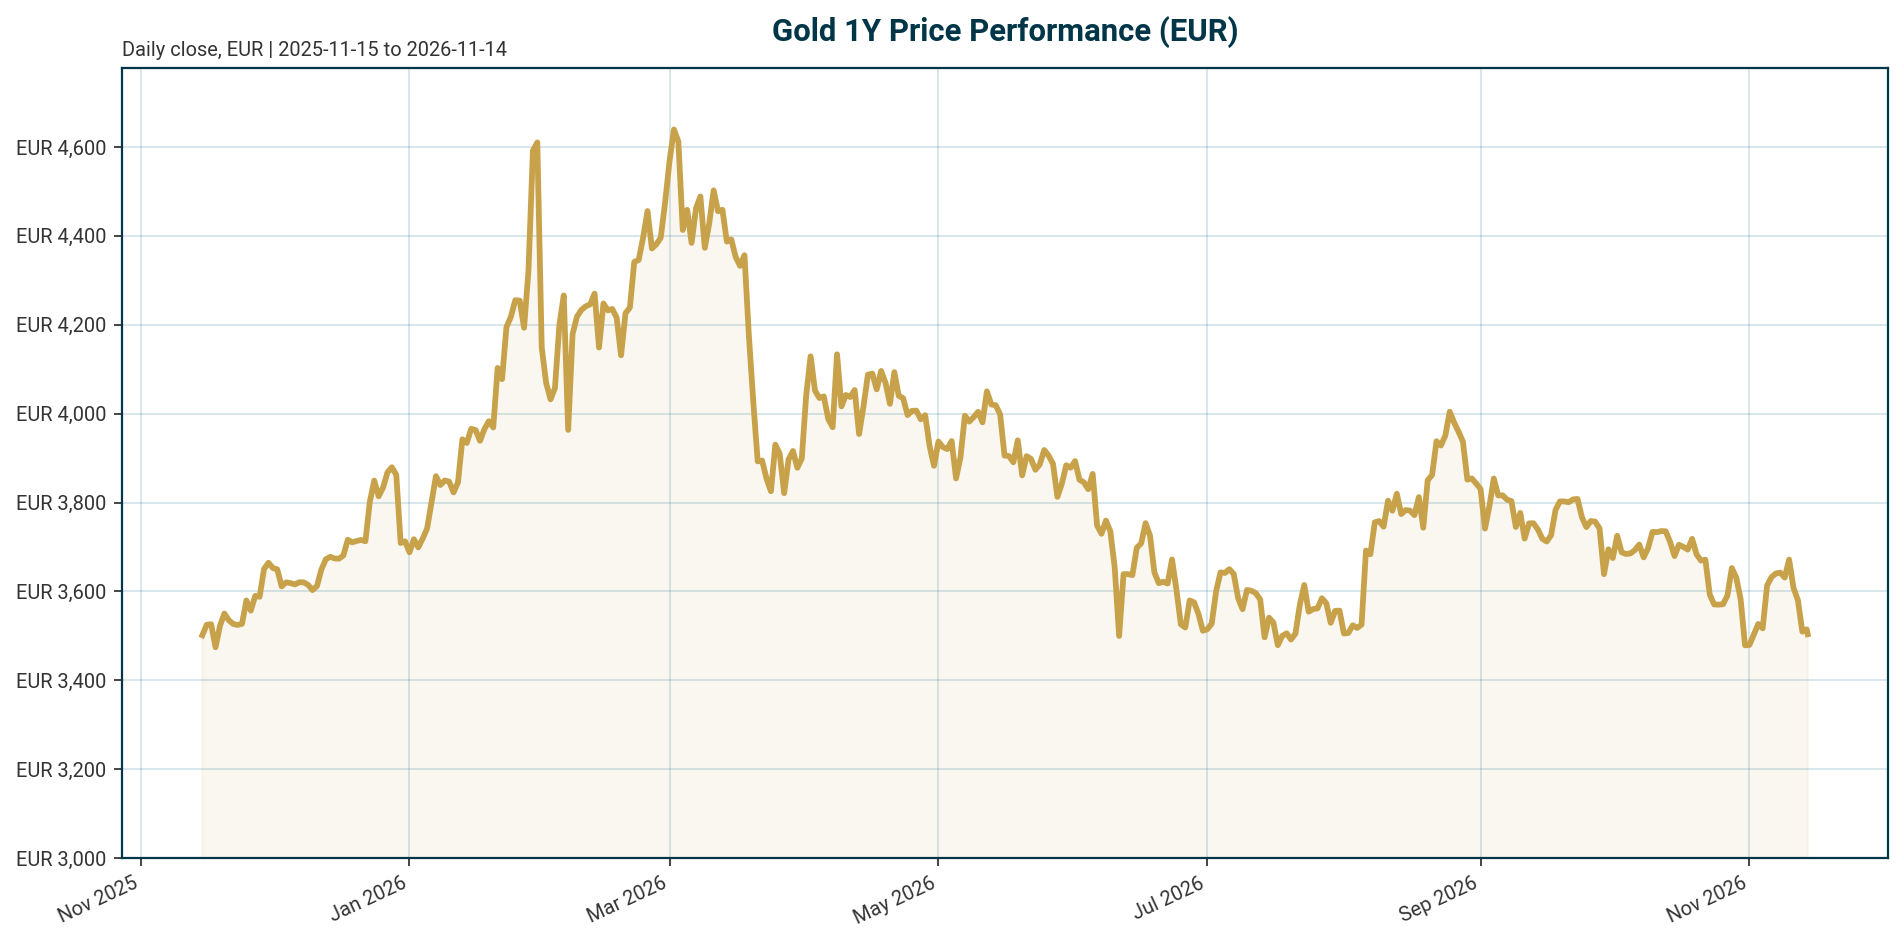
| XAU price (EUR, via PAXG proxy) | EUR 3,504.31 | -0.81% (24h), range 3,499.11 to 3,532.01 |
| 7-day / 30-day change | -5.04% / -6.85% | Corrective phase |
| 200-day / 1-year change | -17.16% / -7.89% | Deep correction, negative on the year |
| All-time high (EUR) | EUR 4,688.32 (28 Jan 2026) | -25.25% below ATH |
| All-time low (EUR) | EUR 1,265.28 (17 Nov 2019) | +176.96% above ATL |
| Fed funds target range | 3.75% to 4.00% (as of 2026-11-13) | Last change: hike of 25 bp, effective 2026-09-17 |
| ECB deposit facility rate | 2.50% (as of 2026-11-14) | Last change: hike of 25 bp, effective 2026-09-16 |
| Euro area AAA 10Y yield | 3.37% (as of 2026-11-12) | +8.2 bp over 5 days, +41.9 bp YTD |
| Euro area AAA 10Y-2Y spread | 29.2 bp | 2Y at 3.08%, +96.7 bp YTD; bear flattening |
| EUR/USD | 1.1084 (as of 2026-11-14) | -1.14% over 5 days, -5.67% YTD |
| Token market cap / 24h volume | EUR 1.569 bn / EUR 88.5 m | Reflects the PAXG instrument, not the full gold market |
Drawdown calculation: 3,504.31 / 4,688.32 – 1 = -25.25%. Implied USD cross-check: 3,504.31 x 1.1084 = approximately USD 3,883 per ounce, versus the US$3,970 support level cited in [T7] from November 2026; the gap reflects retrieval-timing and proxy differences.
Macro Backdrop
Market overview: Risk sentiment is neutral while equity momentum is moderately negative. DACH equities are outperforming, averaging +1.62% over five days versus +0.10% for global indicators, with the DAX up 5.74% on a one-month basis and the Nikkei 225 the strongest five-day mover at +4.03%, while the Hang Seng is the weakest at -3.32%. The rates backdrop shows mixed euro yields with a flattening curve: the euro area AAA 10Y yield sits at 3.37%, up 8.2 bp over five days, and the 10Y-2Y spread has compressed to 29.2 bp. On FX, the euro is weaker against the dollar, with EUR/USD at 1.1084, down 1.14% over five days and 5.67% year to date.
For gold, the dominant macro fact is the hawkish turn in policy. The Fed funds target stands at 3.75% to 4.00% after a 25 bp hike effective 17 September 2026, and the ECB deposit facility rate is 2.50% after a 25 bp hike effective 16 September 2026. According to [T7] from November 2026, stronger-than-expected US inflation lifted market-implied odds of a further 25 bp Fed hike in December to roughly 91%, and the dollar reached a 19-month high by 12 November. That is a market expectation, not a decision.
The mechanism matters for positioning. Rising nominal rates that outpace inflation push real yields higher and raise the opportunity cost of holding a non-yielding asset. Conversely, a stagflationary mix of high inflation and low real rates is historically the most bullish regime for gold [T2]. Euro-area nominal yields rising alongside a hawkish Fed means EUR-quoted gold faces pressure from both legs. Euro-area real yields cannot be computed from this dataset because no HICP print is included.
Investment Thesis
The gold market currently trades on a tension between a structural, reserve-driven bid and a cyclical, policy-driven headwind. We hold a balanced stance, with the December Fed decision as the near-term pivot.
The structural bid. Official agencies hold more than 36,000 tonnes of gold, the highest quantity since 1975, and central banks have bought an average of roughly 1,000 tonnes per year over the past four years, double the average of the previous decade [T6]. ECB research shows central bank gold reserves now represent 27% of official reserves, exceeding holdings of US Treasuries at 22% [T6]. Motivations are durable: a shield against sanctions, diversification away from the dollar, and crisis performance, which 90% of surveyed central banks cite [T6]. A record 43% of 73 monetary authorities surveyed expect their own gold reserves to rise over the next year [T1]. As [T4] argues, gold’s strength despite fluctuating rate expectations reflects a structural rather than speculative bid, anchored in debt sustainability and geopolitical fragmentation concerns.
The cyclical headwind. The Fed has hiked into 2026, with the target range at 3.75% to 4.00% after the September hike, and markets price a further December hike at roughly 91% probability according to [T7] from November 2026. The dollar at a 19-month high and gold testing support near US$3,970 in USD terms, as quoted by Ole Hansen of Saxo Bank in [T7], confirm the pressure. Importantly, official-sector demand supports the market but is unlikely to drive short-term price moves; investment flows dominate near term [T3].
Net view. The structural bid caps downside and makes deep drawdowns buyable, but it does not prevent cyclical corrections when real yields rise. Until the Fed’s path clarifies, XAU/EUR is more likely to consolidate its 25% drawdown from the January high than to resume the trend. A Fed pause or inflation rollover would shift the balance decisively in favour of the structural bid.
Bullish Drivers
- Central bank accumulation at record scale. Net purchases hit a record 1,082 tonnes in 2022 and sustained that pace through 2023 and 2024, driven by emerging market central banks [T1]. The World Gold Council raised its expectation for full-year 2026 purchases to at least match 2025 levels [T7].
- Reserve reallocation away from the dollar. Gold at 27% of central bank reserves versus 22% for US Treasuries marks a deliberate shift in reserve management [T6]. This demand is price-insensitive relative to investment flows.
- Geopolitical and sanctions hedging. Nations facing elevated geopolitical risks and countries seeking to reduce dollar vulnerability continue adding reserves [T1]. Energy-price-driven tensions keep inflation risk alive, and a stagflationary backdrop would support gold over the longer term [T3].
- China’s sustained buying. According to [T5], an earlier-vintage source, China’s central bank added 8.1 tonnes in a single month, its largest purchase since December 2024, extending a 15-month buying streak to roughly 2,305 tonnes of total holdings.
- Fed pivot scenarios. The World Gold Council’s 2026 outlook quantifies upside: in a growth-slowdown case with Fed cuts beyond consensus, gold could rise by 5 to 15 percentage points in 2026; in a doom-loop recession case with aggressive cuts and flight-to-safety, by 15 to 30 percentage points [T8]. These are WGC scenario price assumptions, not forecasts of central bank decisions. Applied to the current EUR price, the ranges imply roughly EUR 3,680 to 4,030 and EUR 4,030 to 4,556 respectively.
- Stagflation regime. High inflation combined with low or negative real rates minimizes the opportunity cost of gold and is historically its most bullish environment [T2].
Relative Positioning vs Bitcoin and Ethereum
Context from the bundle: Bitcoin dominance stands at 58.79%, total crypto market capitalization at USD 2.086 trillion, and total crypto 24-hour volume at USD 79.88 billion as of 14 November 2026. The PAXG token’s market cap of EUR 1.569 billion is a rounding error against that figure, though it measures the tokenized instrument, not gold’s total market.
The current backdrop is characterized by resilient demand for hard assets, persistent geopolitical supply risks in energy, and increasingly selective liquidity allocation [T4]. Market debate on Bitcoin centres on whether US$80,000 or US$60,000 is the more likely destination as gold and oil signal persistent inflation risks [T4].
The key structural difference is the buyer base. Gold’s bid includes central banks and sovereign institutions accumulating reserves [T4]; crypto has no official-sector analogue and therefore no comparable price-insensitive floor. In the current hawkish regime, with the Fed at 3.75% to 4.00% and December hike expectations near 91% per [T7] from November 2026, yield-free crypto assets face the same opportunity-cost headwind as gold but without the official-sector support, arguing for gold’s relative defensiveness. Conversely, in an easing pivot, liquidity-sensitive crypto could outperform gold on the upside.
Data gap: No Ethereum price or performance data is present in the dataset, so no quantitative ETH comparison is possible. Ethereum’s relative positioning is unavailable in this report.
Scenario Framework
| Scenario | Triggers | Implication for XAU/EUR |
|---|---|---|
| 1. Hawkish continuation (market-implied) | The December 25 bp Fed hike materializes per the roughly 91% pricing reported in [T7] from November 2026; inflation surprises again; the dollar holds its 19-month high | Real yields stay elevated and the tug-of-war resolves against gold: rising real rates outweigh the inflation-hedge benefit [T2]. XAU/EUR remains under pressure, with the USD support zone near US$3,970 as reference [T7] |
| 2. Baseline pivot (scenario assumption) | Inflation cools; the Fed pauses after December. WGC consensus inputs: global GDP growth stable at trend, around 75 bp of additional Fed cuts priced, dollar edging higher, flat yields [T8] | Gold trades rangebound under the WGC valuation framework [T8]. XAU/EUR consolidates near current levels with two-way risk |
| 3. Stagflation / recession (scenario assumption) | Growth shock forces aggressive Fed cuts; long-term yields fall sharply and the dollar softens [T8]. Alternatively, persistent inflation with stagnant growth keeps real rates low [T2] | WGC quantifies a 5% to 15% price rise in the slowdown case and 15% to 30% in the doom-loop case [T8]. Stagflation is historically the most bullish regime [T2] |
Energy-shock caveat: a supply-driven energy shock lifts inflation but also yields and the dollar, which can pressure gold despite geopolitical escalation, as observed in 2022 [T5]. Geopolitical headlines alone are insufficient; the transmission runs through inflation, policy expectations and real rates [T3].
Euro-area transmission: with the AAA 10Y at 3.37% and the 10Y-2Y spread at just 29.2 bp after a 96.7 bp YTD rise in the 2Y, EUR-quoted gold faces rising euro nominal yields even where USD dynamics ease. A euro recovery would remove the FX cushion that has partially offset USD-side weakness.
Valuation Discussion
XAU/EUR at 3,504.31 sits 25.25% below the January 2026 ATH of 4,688.32 but remains 176.96% above the 2019 low of 1,265.28. The 200-day change of -17.16% confirms this is a protracted correction, not a one-off shock.
Framework read: the World Gold Council’s Gold Valuation Framework, fed with market consensus variables (global GDP growth stable and broadly in line with trend, around 75 bp of additional Fed cuts priced by markets, core CPI/PCE down 40 to 60 bp by year-end, a modestly higher dollar, flat yields), implies rangebound gold performance [T8]. These are consensus macro inputs from the WGC, not policy rate levels. Under that lens, the current 25% drawdown looks closer to a fair-value correction within a structurally supported market than a regime break.
Positioning read: an earlier-vintage source noted gold up roughly 6% year to date at its publication, leaving the market vulnerable to profit-taking, with deeper pullbacks likely to attract central bank and long-term buyer demand [T3]. Per [T7] from November 2026, gold in USD terms dipped below US$4,000 and tested approximately US$3,970 support on 12 November as the dollar hit a 19-month high. Our EUR/USD cross-check implies roughly USD 3,883 at retrieval, suggesting the EUR-quoted price has already traded through that USD reference, partly because the euro’s YTD weakness of 5.67% cushions EUR-quoted gold.
Yield caveat: gold produces no yield, so its relative value falls as real rates rise [T7]. The dataset contains no US real yield (TIPS) series and no euro-area HICP print, so real-rate arguments here rest on source commentary rather than a computable series. Euro-area real yields are not computable from the bundle.
Verdict: neither cheap nor rich in absolute terms; the price is consistent with consensus macro inputs. The asymmetry lies in the scenarios: consensus inputs imply rangebound trade, while deviation scenarios (Fed cuts beyond consensus, stagflation) are quantified by the WGC at price upside of 5% to 30% depending on severity [T8]. The hawkish-continuation scenario is the main downside risk to that asymmetry.
Risks
Downside risks:
- Further Fed tightening: December hike expectations near 91% per [T7] from November 2026, a stronger dollar at a 19-month high, and rising real yields all increase the opportunity cost of gold [T2, T7].
- Central bank buying may slow: ING notes purchases slowed in early 2026 and ETF outflows weighed on prices [T3]. Official demand supports but does not drive short-term prices [T3].
- Energy-shock dynamics: supply-driven energy price spikes lift yields and the dollar and can pressure gold despite geopolitical escalation, as in 2022 [T5].
- FX reversal: a euro recovery would strip out the EUR/USD cushion that has partially offset USD-side weakness for euro-based holders.
Upside risks (to a bearish position):
- A growth or financial shock would trigger flight-to-safety demand; 90% of surveyed central banks cite gold’s crisis performance as a reason to hold it [T6, T8].
- Fed leadership transition uncertainty, noted in an earlier-vintage source [T5], adds a policy-path risk that could revive safe-haven demand abruptly.
Data and model risks: the dataset lacks a US real yield series, a euro-area HICP print, and any Ethereum price data. Several Tavily sources are undated and of mixed vintages; figures from them are attributed and treated as historical context, never as current state. The EUR price is sourced from the PAXG tokenized gold instrument, which can deviate modestly from spot.
Appendix
Data provenance. Price, volume and market cap data are quoted in EUR via the PAXG tokenized gold instrument (coingecko_id: pax-gold), retrieved 2026-11-14T05:20Z. The reported market cap of EUR 1.569 billion reflects the tokenized instrument, not the full gold market. Policy rates are sourced exclusively from the bundle’s Policy Rates block: US Federal Funds Target Range of 3.75% to 4.00% as of 2026-11-13, last change a 25 bp hike effective 2026-09-17; ECB Deposit Facility Rate of 2.50% as of 2026-11-14, last change a 25 bp hike effective 2026-09-16. Euro-area AAA yields are from the ECB yield curve as of 2026-11-12; FX rates are from Frankfurter as of 2026-11-14; equity indices are as of 2026-11-13.
Source vintage handling. Tavily sources T1 to T8 are largely undated. Only T7 (13 November 2026) and T4 (10 November 2026, inferred from its URL) are datable. Sources T3 and T5 reference earlier Fed easing debates and payrolls data that predate the current hiking-cycle policy rates; they are used as historical and framework context only, never as the current state. Central bank holdings figures differ modestly across sources (over 35,000 tonnes in [T2] versus over 36,000 tonnes in [T6]; survey records of 43% in [T1] versus 45% in [T6]); the more recent or better-attributed figure is used and discrepancies are noted. WGC scenario figures (GDP growth assumptions and gold price upside ranges) are quoted as scenario assumptions from [T8] and are distinct from central bank policy rates.
Glossary. Real yield: a nominal bond yield minus expected inflation, the key opportunity-cost measure for non-yielding gold. 10Y-2Y spread: the gap between 10-year and 2-year yields; compression signals curve flattening. Central bank net purchases: official-sector gross buying minus gross selling of gold. BTC dominance: Bitcoin’s share of total crypto market capitalization. Drawdown from ATH: the percentage decline from the all-time high.
Sources
- [T1] Is it a golden era for gold? | J.P. Morgan Private Bank U.S.
- [T2] Gold, Inflation and Interest Rates: How Do They Interact?
- [T3] Geopolitics alone isn’t enough to lift gold | ING THINK
- [T4] Does $80,000 Bitcoin remain more likely than $60,000 as Gold and Oil signal persistent inflation risks?
- [T5] Why gold isn’t acting like a safe haven right now | ING THINK
- [T6] Central bank gold holdings are at a 50-year high. What’s behind the jump in reserves?
- [T7] Central Bank Gold Buying Surges 42% as Prices Dip Below US$4000
- [T8] Gold Outlook 2026: Push ahead or pull back | World Gold Council
Disclaimer: This report is AI-generated and for informational purposes only. It does not constitute investment advice, a recommendation, or an offer to buy or sell any financial instrument. Data may be incomplete, delayed, or inaccurate, and scenario assumptions are not forecasts. Readers should conduct their own research and consult a licensed financial advisor before making investment decisions.
Important Note / Wichtiger Hinweis:
EN: This report may have been generated using AI. It processes data from publicly available sources. The content is provided for informational purposes only.DE: Dieser Bericht kann mithilfe von KI erstellt worden sein. Dabei werden Daten aus öffentlich zugänglichen Quellen verarbeitet. Die Inhalte dienen ausschließlich Informationszwecken.