Watch the video
This player shows only the Bitcoin chapter of the daily altii market briefing. Watch the full video on tube.altii.de.
Key Data Snapshot
| Metric | Value |
|---|---|
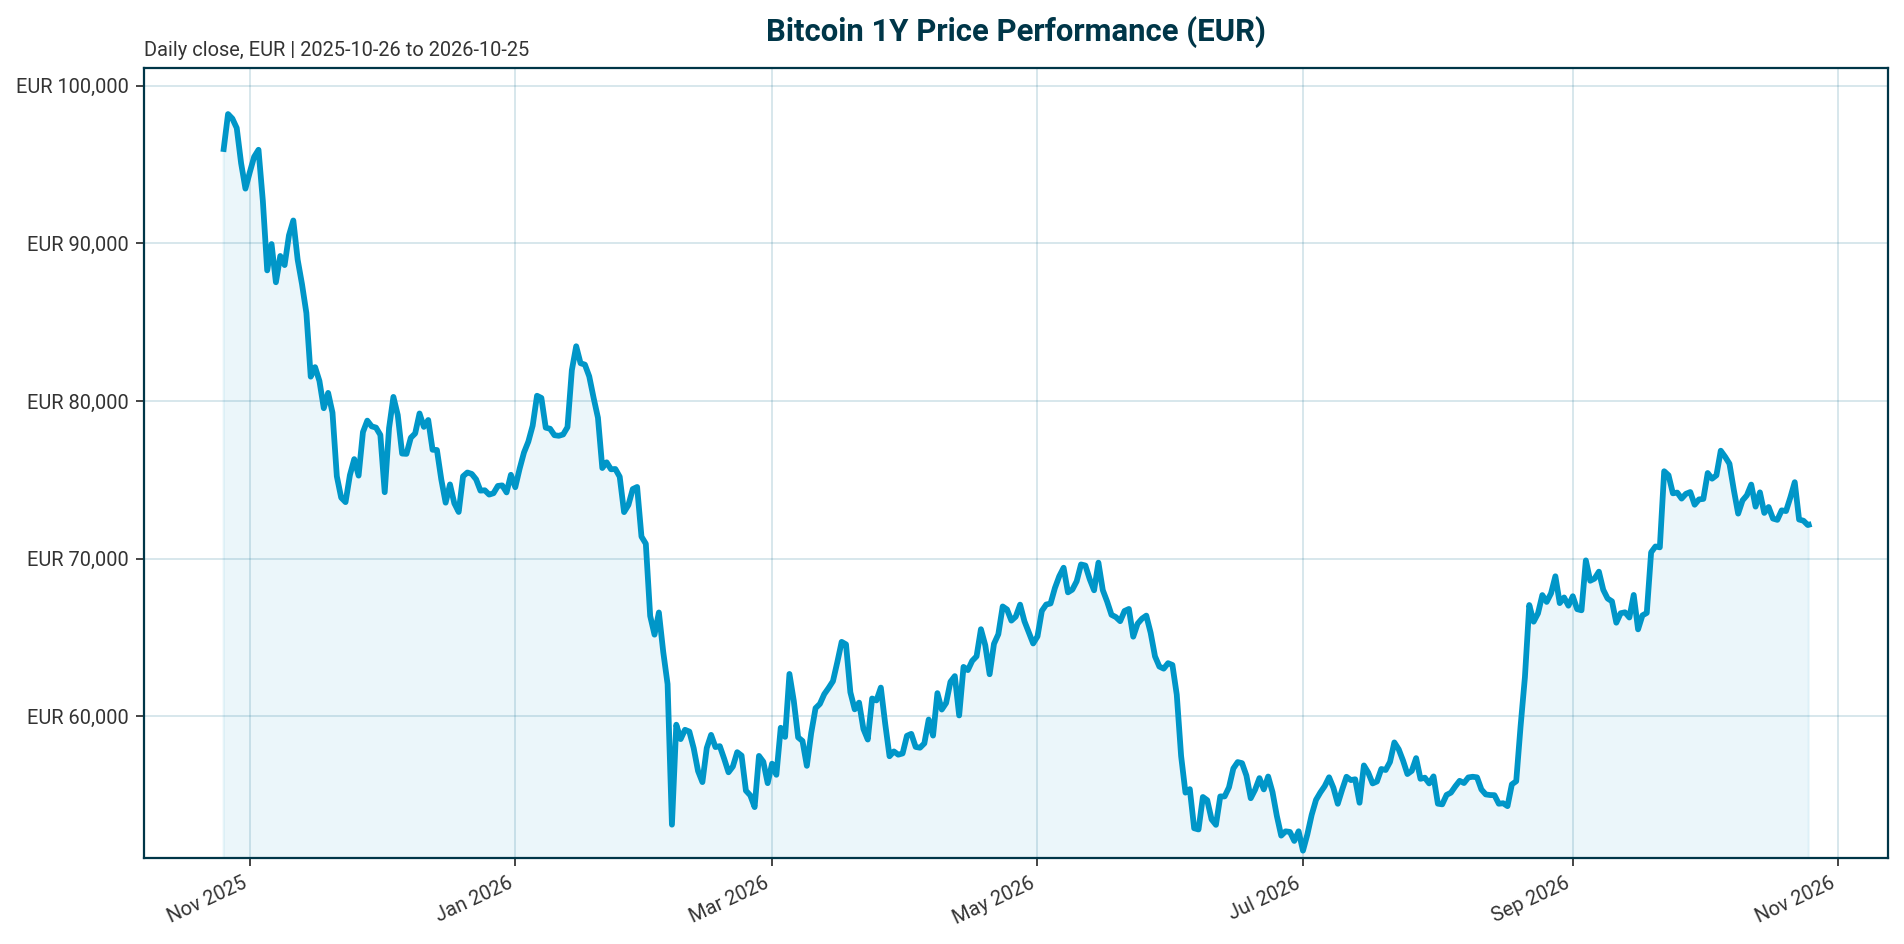
| Price (EUR) | EUR 72,142 |
| 24h range (EUR) | EUR 70,745 to EUR 72,250 |
| 24h volume (EUR) | EUR 18.58 billion |
| Performance 24h / 7d / 14d | +0.05% / -1.24% / -2.29% |
| Performance 30d / 200d / 1y | -3.96% / +13.86% / -27.18% |
| All-time high | EUR 107,662 (2025-10-06); current price -32.99% below |
| Market cap / FDV | EUR 1.45 trillion / EUR 1.45 trillion (rank 1) |
| BTC dominance | 59.46% of a EUR 2.43 trillion total crypto market cap |
| Supply | 20,103,131 of 21,000,000 BTC circulating (95.73% issued) |
| 24h turnover (volume / market cap) | 18.58bn / 1,450.28bn = 1.28% |
| Gold / ETH benchmark prices | Not in the dataset; positioning discussion is qualitative for gold and flow-based for ETH |
Drawdown check: 72,142 / 107,662 – 1 = -32.99%, matching the bundle figure. Dominance cross-check: 1,450.28bn / 2,433.85bn = 59.59%, consistent with the reported 59.46% after rounding and source differences.
Market Setup
The cross-asset backdrop is defensive. Risk sentiment is negative, equity momentum is broadly negative, and DACH indices are broadly in line with global peers: the DAX is the strongest 5-day performer at -0.55% while the Hang Seng is the weakest at -4.52%. DACH indicators average -2.09% over 5 days versus -2.65% for global equity indicators. Euro-area rates are mixed: the AAA 10Y yield sits at 3.38% after a -6.0 bp move over 5 days, the 2Y is at 3.01%, and the 10Y-2Y spread is 37.7 bp. FX is mixed, with EUR/USD at 1.1219 (-0.11% over 5 days), EUR/JPY at 176.27 and EUR/CHF at 0.9231.
Policy is restrictive. The Federal Funds target range stands at 3.75% to 4.00% as of 2026-10-24, following a 25 bp hike effective 2026-09-17. The ECB deposit facility rate is 2.50% as of 2026-10-25, following a 25 bp hike effective 2026-09-16. Both central banks tightened in September 2026, so a restrictive-rate regime is the working base case for risk assets. According to a Q2 2026 review [T1], the market expected the Fed under Chair Kevin Warsh to hold rates through Q3; this is a dated expectation, not a decision, and the authoritative rate block above takes precedence.
For BTC specifically, the flow channel dominates. A CryptoSlate report described surging US Treasury yields and tightening liquidity pushing BTC back below $82,000 resistance, with ETFs on pace for more than $700 million in weekly outflows, the largest weekly retreat since late January [T6]. The same report noted that higher yields make institutional buyers more selective because government bonds offer a stronger risk-adjusted return [T6]. September US PPI accelerated to 6.3% YoY and 1.3% MoM, its strongest monthly rise since March 2022, according to a dated market report [T4]. These are time-stamped news figures, not current readings. For a EUR-based investor, the drift lower in euro-area long yields is the one incremental supportive element in an otherwise restrictive setup.
Investment Thesis
Bitcoin has become a flow-driven macro asset rather than a narrative-driven one. Fair value is set by the tension between expanding institutional distribution channels and the macro forces that govern risk appetite and real rates [T5]. The practical implication: BTC’s marginal price is determined by ETF flows, liquidity and positioning, not by its issuance curve.
The structural facts support this framing. By the end of 2025, 6.7 million BTC sat across ETFs, exchanges and treasuries, a level Glassnode described as Bitcoin’s “institutional supply era” [T2]. Bitcoin’s volatility fell from 84% to 43% according to the Glassnode x Fasanara report, evidence of institutionalisation, though it also means BTC now trades with sharper macro sensitivity [T2]. Net new mining supply of roughly 160,000 BTC per year is small against ETF holdings of more than 1 million BTC; holder reallocation matters more than mining, and new annual supply equals only about 16% of ETF-held coins [T5]. Whale wallets of 1,000 BTC or more accumulated into the late-2025 fear, suggesting a provisional floor but also a future overhang if macro deteriorates [T5].
The two-sided thesis: if inflows broaden across wealth platforms and eventually retirement channels, the structural bid can overwhelm modest supply growth. But in a tight-liquidity environment, the same ETFs can become forced sellers, and Q4 2025 demonstrated the downside transmission when record outflows coincided with the break of $98,000 support (about EUR 87,350 at today’s EUR/USD) [T2]. With the Fed at 3.75% to 4.00% and the ECB at 2.50% after September hikes, the liquidity side of that equation remains the binding constraint today.
Bullish Drivers
- Retirement-channel expansion. The $22 trillion US 401(k) and Defined Contribution system is the largest untapped ETF demand pool. Even a 1% allocation would generate $90 to 130 billion of steady, rules-based inflows, roughly EUR 80 to 116 billion at EUR/USD 1.1219, on par with the entire current spot BTC ETF market [T5]. These flows are long-duration and less volatility-sensitive, though adoption unfolds gradually.
- Regulatory catalysts. The CLARITY Act would establish a federal market-structure framework for digital assets and could unlock broader institutional participation if passed [T1]. In Asia, Hong Kong’s Stablecoins Ordinance, requiring full reserve backing and redemption rights, is drawing banks and asset managers into tokenised infrastructure [T1].
- Supply scarcity. The hard cap of 21 million coins with 20,103,131 already circulating (95.73% issued) means annual new supply of roughly 160,000 BTC is negligible against a EUR 1.45 trillion market cap [T5].
- Product depth. Deep, liquid options markets on regulated bitcoin ETFs now support covered call, buffered and other derivatives-based income strategies, broadening the addressable investor base to yield-oriented allocators [T1].
- Flow signals, with caveats. US spot bitcoin ETFs attracted $526.7 million of net inflows on October 19, the strongest daily inflow since September 22, led by BlackRock’s IBIT at $665.2 million [T4]. Earlier, weekly inflows reached $1.92 billion according to an August 2026 report [T8]. These are dated figures and one strong session does not establish a trend, but they show the demand channel can reopen quickly.
- Institutional sentiment. A dated analysis claims daily ETF inflows consistently exceeded $400 million and that 94% of institutional investors recognise long-term blockchain value [T3]. Treat these as attributed claims, not verified data.
Relative Positioning vs Gold and Ethereum
Versus Ethereum: the flow divergence is stark. While BTC ETFs took in $526.7 million on October 19, Ether ETFs recorded $103.3 million of net outflows, their fourth consecutive session of withdrawals [T4]. BTC showed relative resilience while ETH and major altcoins stayed weak, with capital favouring institutional-infrastructure themes over broad speculation [T4]. With BTC dominance at 59.46% of a EUR 2.43 trillion market, BTC remains the default institutional crypto allocation vehicle, and continued flow divergence would support further dominance gains. The bearish reading: dominance near 60% also means BTC is the asset most exposed to a coordinated crypto redemption cycle, since it holds the largest institutional positions.
Versus gold: gold spot data is not in the dataset, so the comparison is qualitative. The structural argument favours BTC capturing store-of-value allocation over time; Ark Invest frames BTC as taking market share from gold and projects $1,000,000 by 2030 with a $200,000 2026 milestone, per a dated source [T3]. These are third-party opinions, not house forecasts. Near term, the picture inverts: in a negative risk-sentiment regime with restrictive policy rates, gold’s safe-haven bid competes directly with BTC for the same diversification budgets, and BTC’s -27.18% one-year return suggests it has traded as a risk asset, not as digital gold, through this drawdown.
Scenario Framework
All trigger levels below are USD-quoted from dated sources and converted at EUR/USD 1.1219 for comparison with the EUR 72,142 spot. Conversions are indicative.
| Scenario | Triggers | Reference levels |
|---|---|---|
| Bull | Sustained multi-week ETF inflow breadth across issuers, plus CLARITY Act progress [T1]. Third-party targets: $100,000 to $150,000 range and a JPMorgan $150,000 Q4 2026 projection at 72% confidence, per a dated source [T3]. These are attributed projections, not forecasts. | Confirmation above $84,000 (about EUR 74,874, +3.8% from spot) with flow confirmation [T4]. |
| Base | Restrictive policy persists (Fed 3.75% to 4.00%, ECB 2.50%); ETF flows oscillate; BTC consolidates while the market awaits a catalyst. | Range roughly $81,000 to $84,000 (about EUR 72,199 to EUR 74,874), per dated levels [T4]; spot at EUR 72,142 sits at the lower edge of this range. |
| Bear | Renewed weekly ETF outflows of the more than $700 million magnitude seen previously [T6], combined with tight liquidity, turn ETFs into forced sellers [T5]. Precedent: Q4 2025 record outflows broke $98,000 support (about EUR 87,352) and retested the low $90,000s [T2]. | Loss of the $82,000 area and the 200-day moving average (about EUR 73,092, +1.3% from spot) would signal continuation lower [T6]. |
The asymmetry is notable: the base-case range is narrow and the spot price sits near its lower bound, while the bear trigger is only 1.3% above spot in EUR terms. Flow data over the next several sessions is the decisive input.
Valuation Discussion
Traditional valuation anchors are limited: BTC has no cash flows, and the bundle contains no on-chain data such as MVRV, realised price or exchange balances, so on-chain-based valuation is unavailable. Two frameworks apply.
Flow-based valuation. Fair value is a function of expected net ETF demand against available supply. The bullish third-party models assume sustained heavy inflows: the $100,000 to $150,000 2026 range rests on daily inflows exceeding $400 million, a claim from a dated promotional analysis [T3]. If inflows normalise below that pace, the input basis for those targets disappears and lower fair-value estimates follow. The 401(k) scenario of $90 to 130 billion in annual rules-based demand [T5] is the largest single upside variable but unfolds over years, not quarters.
Scarcity-based valuation. With 95.73% of the 21 million cap issued and FDV equal to market cap at EUR 1.45 trillion, there is no unlock overhang and no dilution cliff. Annual new supply of roughly 160,000 BTC equals about 0.8% of circulating supply, so price is set almost entirely by holder reallocation [T5]. Scarcity supports a floor narrative only if existing holders do not distribute into strength; whale accumulation to date suggests a provisional floor, with the caveat of a future overhang [T5].
Relative valuation. At EUR 1.45 trillion, BTC is priced at a meaningful discount to its October 2025 peak valuation and 32.99% below its ATH. Whether that is cheap depends on the flow regime: in an easing cycle this discount would look attractive; at a 3.75% to 4.00% Fed funds range with the ECB at 2.50%, the required risk premium is higher and the discount looks more proportionate.
Risks
- Macro and rates risk. The Fed target range of 3.75% to 4.00% and the ECB rate of 2.50%, both raised in September 2026, keep liquidity restrictive. Higher yields make institutional buyers more selective because government debt offers a stronger return profile [T6]. September US PPI at 6.3% YoY, per a dated source [T4], if indicative of persistent inflation, limits any near-term easing path.
- Flow concentration risk. The October 19 inflow was concentrated in IBIT at $665.2 million while other funds saw withdrawals; one strong session does not establish a durable accumulation trend [T4].
- Forced-seller risk. In tight liquidity, ETFs become the transmission mechanism for drawdowns, converting redemptions directly into spot selling [T5].
- Structural overhang risk. Whale wallets holding 1,000 BTC or more accumulated into weakness; those positions are a future supply overhang if macro deteriorates [T5].
- Regulatory risk. CLARITY Act passage is uncertain; failure or delay removes a key catalyst and shifts the bull case entirely onto flow breadth [T1].
- Data and currency risk. Several news items lack publication dates, and most technical levels are USD-quoted while this report is EUR-quoted. The USD levels cited ($81,000 to $84,000) imply USD prices well above the EUR spot after conversion, reflecting timing and FX drift; all source levels are explicitly dated and should not be read as current EUR prices.
- Balanced view. Against these risks, the 200-day change of +13.86%, falling volatility [T2], and demonstrated capacity of the ETF channel to absorb over $1.9 billion in a single week [T8] are genuine offsets. The structure is intact; the liquidity cycle is the problem.
Appendix
Policy rate reference. US Federal Funds Target Range: 3.75% to 4.00% as of 2026-10-24; last change a 25 bp hike effective 2026-09-17. ECB Deposit Facility Rate: 2.50% as of 2026-10-25; last change a 25 bp hike effective 2026-09-16. No other central bank rates are in the dataset.
Methodology notes. Market data retrieved 2026-10-25 05:15 UTC from CoinGecko; equity, rates and FX data as of 2026-10-22 to 2026-10-25. USD-quoted levels from news sources are converted at EUR/USD 1.1219 and labelled as indicative. Gold spot and ETH spot prices are not in the dataset; the gold comparison is qualitative and the ETH comparison relies on dated flow data. Several Tavily items lack publication dates; all news-derived figures are attributed and dated where possible, and none should be read as current market state.
Sources
- [T1] Q2 2026 Digital Asset Review, CoinDesk Indices: link
- [T2] Crypto Market 2025: Year-End Review & Expert Insights, TradingView News: link
- [T3] Bitcoin Price Prediction 2026: Institutional Adoption & ETF Impact Analysis, Intellectia: link
- [T4] Bitcoin Holds the Line, Altcoins Falter as Crypto Enters a New Institutional Cycle, MarinaTimes NG: link
- [T5] Bitcoin 2026 outlook: ETF gravity vs. Macro ceiling, 21Shares: link
- [T6] US Treasury yields surge to new highs as liquidity tightens, pushing Bitcoin back below $82,000 resistance, CryptoSlate: link
- [T7] Bitcoin ETFs Absorb $134.4M as Macro Backdrop Improves, Elevano Capital via LinkedIn: link
- [T8] Bitcoin ETF Inflows Surge to $1.92 Billion Last Week, Cryptonomist, August 2026: link
Disclaimer. This report is AI-generated and provided for informational purposes only. It does not constitute investment advice, a recommendation, or an offer to buy or sell any financial instrument. Scenarios and trigger levels are assumptions, not forecasts. Third-party price targets are attributed to their sources and are not endorsed. Data may be incomplete, dated, or subject to revision; readers should verify all figures independently before making investment decisions.
Important Note / Wichtiger Hinweis:
EN: This report may have been generated using AI. It processes data from publicly available sources. The content is provided for informational purposes only.DE: Dieser Bericht kann mithilfe von KI erstellt worden sein. Dabei werden Daten aus öffentlich zugänglichen Quellen verarbeitet. Die Inhalte dienen ausschließlich Informationszwecken.
* DE: Die ergänzenden Inhalte können KI-generiert sein. EN: The additional content may be AI-generated.