Watch the video
This player shows only the Bitcoin chapter of the daily altii market briefing. Watch the full video on tube.altii.de.
Key Data Snapshot
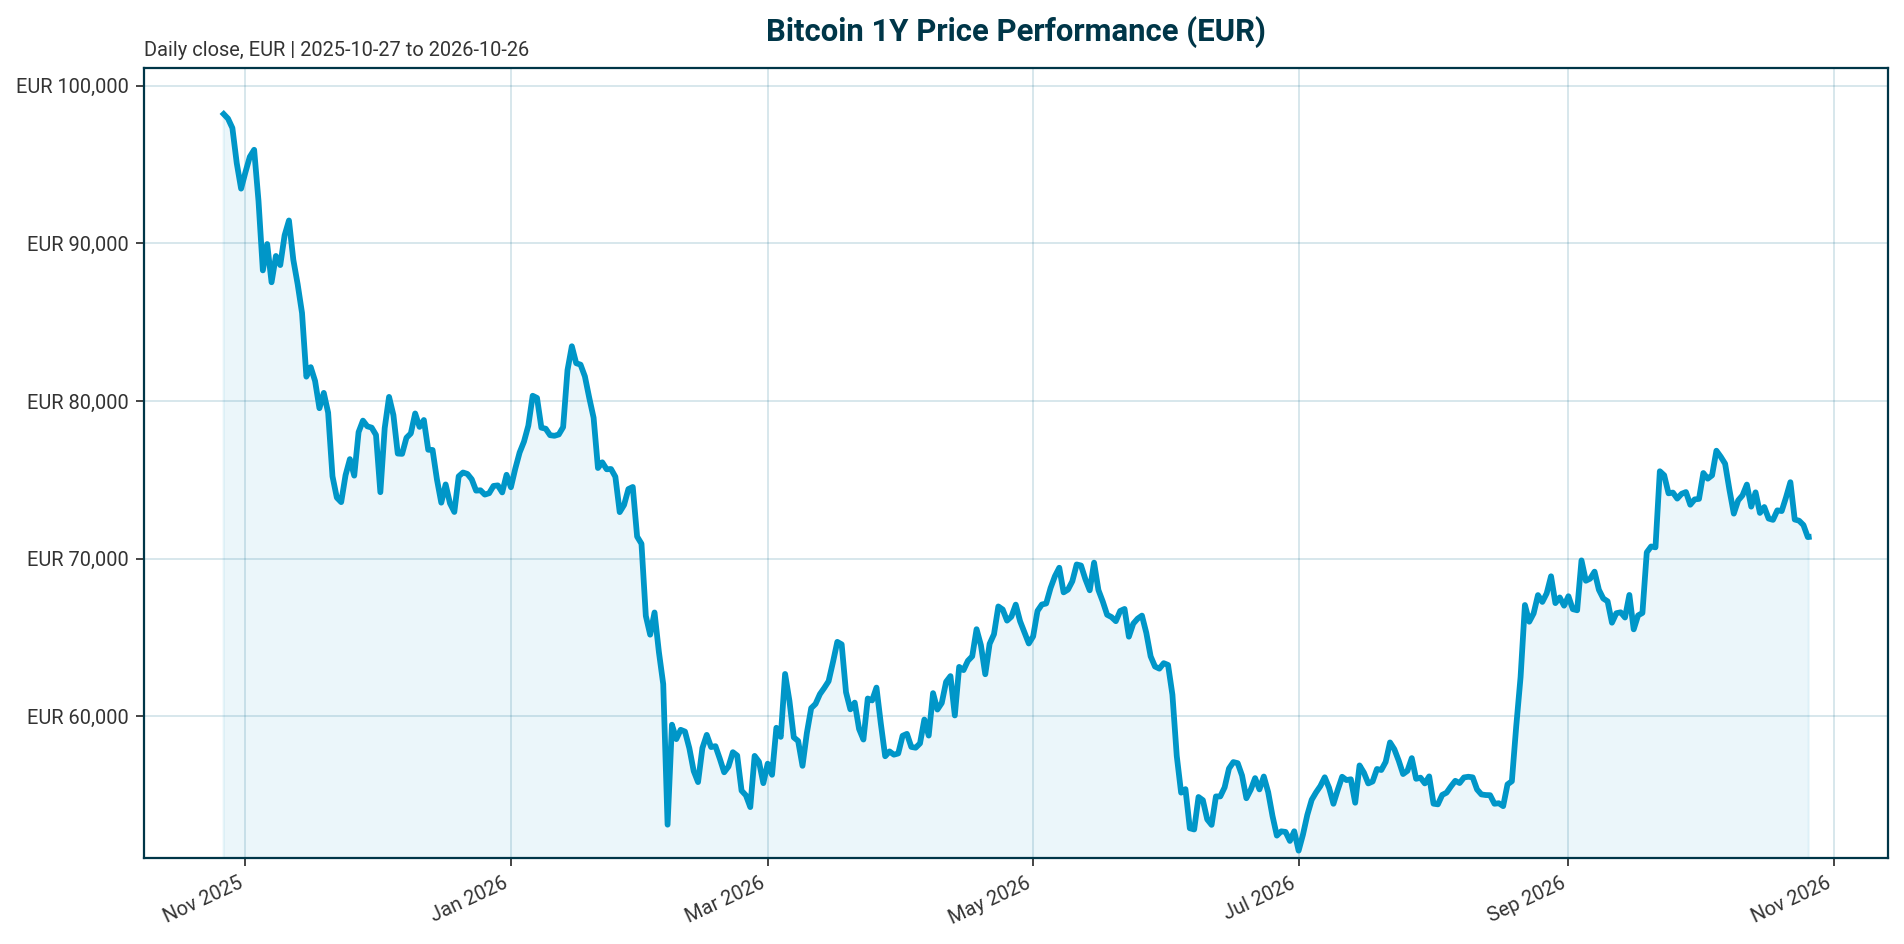
Bitcoin (BTC) trades at EUR 71,329 as of 26 October 2026, down 1.09% over 24 hours and 4.67% over 30 days. The asset sits 33.75% below its all-time high of EUR 107,662 set on 6 October 2025, while remaining up 13.34% over 200 days. The picture is a corrective phase inside a longer-term uptrend, with flow dynamics rather than supply shocks setting the price.
| Metric | Value |
|---|---|
| Price (EUR) | 71,329 (24h range: 70,699 to 72,030) |
| Market cap | EUR 1.434 trillion (rank 1) |
| 24h volume | EUR 15.89 billion (turnover: 15.89bn / 1,433.69bn = ~1.11% of market cap) |
| BTC dominance | 60.02% (cross-check: 1,433.69bn / 2,386.01bn total crypto cap = 60.08%) |
| Performance ladder | +0.61% (1h), -1.09% (24h), -2.97% (7d), -4.23% (14d), -4.67% (30d), +13.34% (200d), -28.10% (1y) |
| All-time high | EUR 107,662 (2025-10-06); current drawdown -33.75%; recovery to ATH requires +50.9% |
| Supply | 20,103,596 of 21,000,000 BTC issued (95.73%); FDV EUR 1.434 trillion |
Market Setup
The cross-asset backdrop is defensive. Risk sentiment is negative and equity momentum is broadly negative, with DACH indices broadly in line with global peers: the DAX is the strongest 5-day performer at -0.55%, the ATX the weakest at -3.63%, and the DACH average of -2.09% over 5 days compares with -1.92% for global equity indicators. The S&P 500 sits at 7,623.68 (-0.87% over 5 days) and the Nasdaq Composite is -1.80% over 5 days. Euro-area rates are mixed: the AAA 10Y yield is 3.38% after a 6.0 bp drop over 5 days, the AAA 2Y is 3.01%, and the 10Y-2Y spread stands at 37.7 bp. FX is mixed, with EUR/USD at 1.1217 (-0.17% over 5 days), EUR/JPY at 176.15 and EUR/CHF at 0.92349.
Policy is restrictive on both sides of the Atlantic. The US Federal Funds target range is 3.75% to 4.00% as of 2026-10-25, following a 25 bp hike effective 2026-09-17. The ECB deposit facility rate is 2.50% as of 2026-10-26, following a 25 bp hike effective 2026-09-16. This configuration caps high-beta asset valuations. Dated news context reinforces the point: according to [T3], September US PPI accelerated to 6.3% YoY, and [T5] reports a US Treasury yield surge and liquidity tightening that pushed Bitcoin back below USD 82,000 resistance. These are dated source figures, not the current state.
One reconciliation note: the current EUR price of 71,329 implies roughly USD 80,000 at EUR/USD 1.1217 (71,329 × 1.1217 ≈ 80,010), consistent with the lower end of the USD 81,000 to 83,000 range cited in [T3]. The USD levels in the news flow are dated context and sit close to, but slightly above, the current market.
Investment Thesis
Bitcoin has become a flow-driven macro asset, and its fair value is set by the tension between expanding institutional distribution and restrictive liquidity. ETF flows now function as Bitcoin’s new macro indicator: according to [T1], record Q4 outflows from US-listed BTC and ETH ETFs coincided with the break of USD 98,000 support and a retest of the low USD 90,000 range. By the end of 2025, 6.7 million BTC sat across ETFs, exchanges and treasuries, a configuration Glassnode described as the “institutional supply era” [T1].
The structural case rests on three pillars. First, demand is shifting from episodic speculation to systematic, rules-driven flows across wealth management and, eventually, retirement channels [T4]. Second, net new mining supply of roughly 160,000 BTC per year is small against more than 1 million BTC in ETFs, so holder reallocation, not mining, drives marginal price [T4]. Third, volatility has compressed from 84% to 43%, supporting institutional portfolio integration [T1]. The bear counterweight is explicit: in a tight-liquidity environment, the same ETFs can become forced sellers [T4]. Whale wallets of 1,000 BTC or more accumulated into recent fear, suggesting a provisional floor but also a future overhang if macro deteriorates [T4]. Meanwhile, Strategy (formerly MicroStrategy) has reportedly slowed purchases amid weaker financing conditions, removing one corporate bid [T8].
Base case (scenario): BTC consolidates while the thesis awaits validation through sustained multi-session ETF inflows and a confirmed move above USD 84,000 [T3], equivalent to roughly EUR 74,900 at EUR/USD 1.1217.
Bullish Drivers
- Flow reversal signal: US spot Bitcoin ETFs attracted USD 526.7 million of net inflows on October 19, the strongest daily inflow since September 22, led by BlackRock’s IBIT at USD 665.2 million (roughly EUR 593 million at 1.1217), according to [T3]. Caveat: other funds recorded withdrawals, so one concentrated session does not establish a durable accumulation trend [T3].
- Retirement channel optionality: the USD 22 trillion US 401(k) and Defined Contribution system could, at a 1% allocation, generate USD 90 to 130 billion of steady, rules-based inflows, on par with the entire current spot BTC ETF market, per [T4].
- Institutional breadth: 94% of institutional investors recognize the long-term value of blockchain technology, and daily ETF inflows reportedly exceeded USD 400 million in earlier 2026 periods, according to [T2] (dated source, not current state).
- Analyst projections (external views, not this report’s forecasts): JPMorgan’s flow-based model projects a USD 150,000 peak target with 72% confidence targeting Q4 2026, and Ark Invest maintains a USD 200,000 2026 milestone and USD 1,000,000 by 2030 [T2]. At EUR/USD 1.1217, these correspond to roughly EUR 133,700 and EUR 178,300 respectively.
- Regulatory tailwinds: clearer stablecoin and market-structure rules could broaden institutional participation [T7].
- Corporate adoption: treasuries increasingly treat BTC as a strategic reserve asset and an allocatable line item for registered investment advisors, private banks and institutions [T1] [T2].
Relative Positioning vs Gold and Ethereum
Versus Ethereum, Bitcoin holds clear relative strength. Ether ETFs recorded USD 103.3 million of net outflows, a fourth consecutive session of withdrawals, while Bitcoin attracted renewed institutional demand in the same period [T3]. Capital selectively favored BTC and institutional infrastructure themes over broader altcoin speculation, and BTC’s 60.02% dominance underscores its role as the crypto anchor while altcoins falter [T3]. Within crypto allocations, the flow evidence favors BTC over ETH.
Versus gold, the comparison is qualitative because the current gold price is not in the dataset. The competitive dynamic is two-sided. Bullishly, Ark Invest frames BTC as capturing market share from traditional store-of-value assets like gold [T2]. Bearishly, higher government bond yields have made institutional buyers more selective because government debt now offers a stronger return profile [T5], which strengthens the competition from fixed income and, by extension, yield-bearing substitutes for the same store-of-value allocation. In a restrictive-rate regime with the Fed at 3.75% to 4.00% and the ECB at 2.50%, gold and bonds outcompete BTC for duration-free store-of-value capital; any rate relief would reverse this relative drag (scenario assumption).
Scenario Framework
- Bull scenario: Sustained multi-week ETF inflows plus price and flow confirmation above USD 84,000 (roughly EUR 74,900 at 1.1217) [T3]. Triggers include broadening wealth-management distribution, any 401(k)/DC adoption progress [T4], and a dovish repricing of Fed expectations (market expectation, not a decision in this dataset). EUR-quoted upside is amplified if EUR/USD weakens from 1.1217.
- Base scenario: Range-bound consolidation between roughly USD 81,000 and 84,000 [T3], with episodic inflows and outflows. BTC tracks equity risk sentiment in the current negative regime. The current implied USD price of ~80,000 sits just below this band, so the market is testing the lower boundary.
- Bear scenario: Renewed weekly outflow streaks, such as the more than USD 700 million weekly retreat reported in [T5], turn ETFs into forced sellers in a tight-liquidity environment [T4]. The whale overhang releases and the drawdown extends beyond the current -33.75% from ATH. EUR-quoted downside is cushioned only partially by euro strength.
Valuation Discussion
Bitcoin lacks cash-flow-based valuation anchors, so valuation here is structural and positional. On supply, 95.73% of the 21 million max supply is issued, and annual mining issuance of roughly 160,000 BTC equals about 0.80% of circulating supply (160,000 / 20,103,596), quantifying supply-side inertia. The FDV of EUR 1.434 trillion nearly equals market cap, reflecting near-complete issuance; price discovery is therefore entirely demand-side [T4].
On positioning, BTC at -33.75% from ATH against a +13.34% 200-day return describes mid-cycle corrective positioning, not a fresh breakout or a full collapse. Volatility compression from 84% to 43% [T1], while lacking a defined measurement window and methodology, is directionally supportive: lower realized volatility allows larger institutional allocation sizing and a structurally higher demand curve, though a volatility spike would reverse this.
Third-party models provide reference points only. JPMorgan’s USD 150,000 flow-based peak target (72% confidence, Q4 2026) and Ark Invest’s USD 200,000 (2026) and USD 1,000,000 (2030) projections [T2] convert to roughly EUR 133,700, EUR 178,300 and EUR 891,400 at EUR/USD 1.1217. These are external projections with unverifiable methodologies and are not forecasts of this report. Fair value remains flow-determined: the tension between expanding distribution and macro forces on real rates and risk appetite [T4].
Risks
- Restrictive policy baseline: Fed funds at 3.75% to 4.00% (hike effective 2026-09-17) and ECB deposit rate at 2.50% (hike effective 2026-09-16). Higher-for-longer rates pressure high-beta valuations [T7]. A further hike is not assumed; any future move is a market expectation requiring dated attribution.
- ETF flow reversal: in tight liquidity, ETFs can become forced sellers [T4]. Weekly outflows exceeded USD 700 million in the referenced period, the largest weekly retreat since late January [T5].
- Demand concentration: the October 19 inflow was led by IBIT at USD 665.2 million while other funds saw withdrawals; one strong session does not establish a durable trend [T3].
- Corporate buyer retrenchment: Strategy (formerly MicroStrategy) has slowed purchases amid weaker financing conditions, removing a corporate bid [T8].
- Inflation risk: September US PPI at 6.3% YoY per [T3] (dated source) could keep policy restrictive and is the primary tail risk to the bull case.
- Whale overhang: wallets holding 1,000 BTC or more represent future supply if macro deteriorates [T4].
- Two-way volatility: institutional participation amplifies volatility in outflows just as in rallies [T8].
- Data limitations: no current gold price, no current ETH/EUR price, and no authoritative current ETF flow data in the dataset; flow trends cannot be verified as of 2026-10-26.
Appendix
Methodology and Data Provenance
All BTC figures are quoted in EUR from CoinGecko data retrieved 2026-10-26T05:15:08Z. News flow figures are USD-denominated; conversions use EUR/USD at 1.1217 and state the rate applied. Policy rates come from the authoritative bundle block: US Federal Funds target range 3.75% to 4.00% (as of 2026-10-25, last change a 25 bp hike effective 2026-09-17) and ECB deposit facility rate 2.50% (as of 2026-10-26, last change a 25 bp hike effective 2026-09-16). Euro-area yield curve data is from the ECB AAA curve as of 2026-10-22; equity and FX data are as of 2026-10-23 to 2026-10-26. News items T1 to T8 are dated or undated secondary sources; USD price levels and flow figures are repeated only with source attribution and are dated context, not the current state. The current gold spot price and the current ETH/EUR price are not in the dataset; benchmark comparisons are qualitative or flagged as missing. Report profile: crypto_institutional; benchmarks: gold and ethereum; generated for altii.
Key Calculations
- Supply issuance: 20,103,596 / 21,000,000 = 95.73%.
- Drawdown from ATH: (71,329 – 107,662) / 107,662 = -33.75%; recovery to ATH requires +50.9%.
- Mining issuance as share of supply: ~160,000 / 20,103,596 = ~0.80% per year.
- 24h turnover: 15.89bn / 1,433.69bn = ~1.11%.
- Dominance cross-check: 1,433.69bn / 2,386.01bn = 60.08% (vs reported 60.02%; rounding and provenance difference).
- USD to EUR conversions at 1.1217: USD 84,000 ≈ EUR 74,900; USD 150,000 ≈ EUR 133,700; USD 200,000 ≈ EUR 178,300; USD 1,000,000 ≈ EUR 891,400.
- Implied USD price: EUR 71,329 × 1.1217 ≈ USD 80,010.
Sources
- [T1] Crypto Market 2025: Year-End Review & Expert Insights, TradingView News
- [T2] Bitcoin Price Prediction 2026: Institutional Adoption & ETF Impact Analysis, Intellectia
- [T3] Bitcoin Holds the Line, Altcoins Falter as Crypto Enters a New Institutional Cycle, MarinaTimes NG
- [T4] Bitcoin 2026 outlook: ETF gravity vs. Macro ceiling, 21Shares
- [T5] US Treasury yields surge to new highs as liquidity tightens, pushing Bitcoin back below $82,000 resistance, CryptoSlate
- [T6] Bitcoin ETFs Absorb $134.4M as Macro Backdrop Improves, Elevano Capital (LinkedIn)
- [T7] Amplify Transformational Data Sharing ETF (BLOK): Blockchain Exposure Amid Regulatory and Macro Shifts, Tickeron
- [T8] Bitcoin Outlook: ETF Outflows, Institutional Adoption & Price Forecast 2026, IG South Africa
Disclaimer
This report is AI-generated and is provided for informational purposes only. It does not constitute investment advice, a recommendation, or an offer to buy or sell any financial instrument. Figures are drawn from the data sources cited and may be incomplete, delayed, or revised. Readers should conduct their own research and consult a licensed advisor before making investment decisions.
Important Note / Wichtiger Hinweis:
EN: This report may have been generated using AI. It processes data from publicly available sources. The content is provided for informational purposes only.DE: Dieser Bericht kann mithilfe von KI erstellt worden sein. Dabei werden Daten aus öffentlich zugänglichen Quellen verarbeitet. Die Inhalte dienen ausschließlich Informationszwecken.
* DE: Die ergänzenden Inhalte können KI-generiert sein. EN: The additional content may be AI-generated.