The altii-Gold-Report: Gold (XAU) in EUR
Watch the video
This player shows only the Gold chapter of the daily altii market briefing. Watch the full video on tube.altii.de.
Key Data Snapshot
| Metric | Value | Interpretation |
|---|---|---|
| XAU/EUR spot | €3,753.23 | As of 2026-10-13 04:53:47 UTC |
| 1h / 24h / 7d | +0.21% / +0.34% / +1.10% | Short-term momentum is positive |
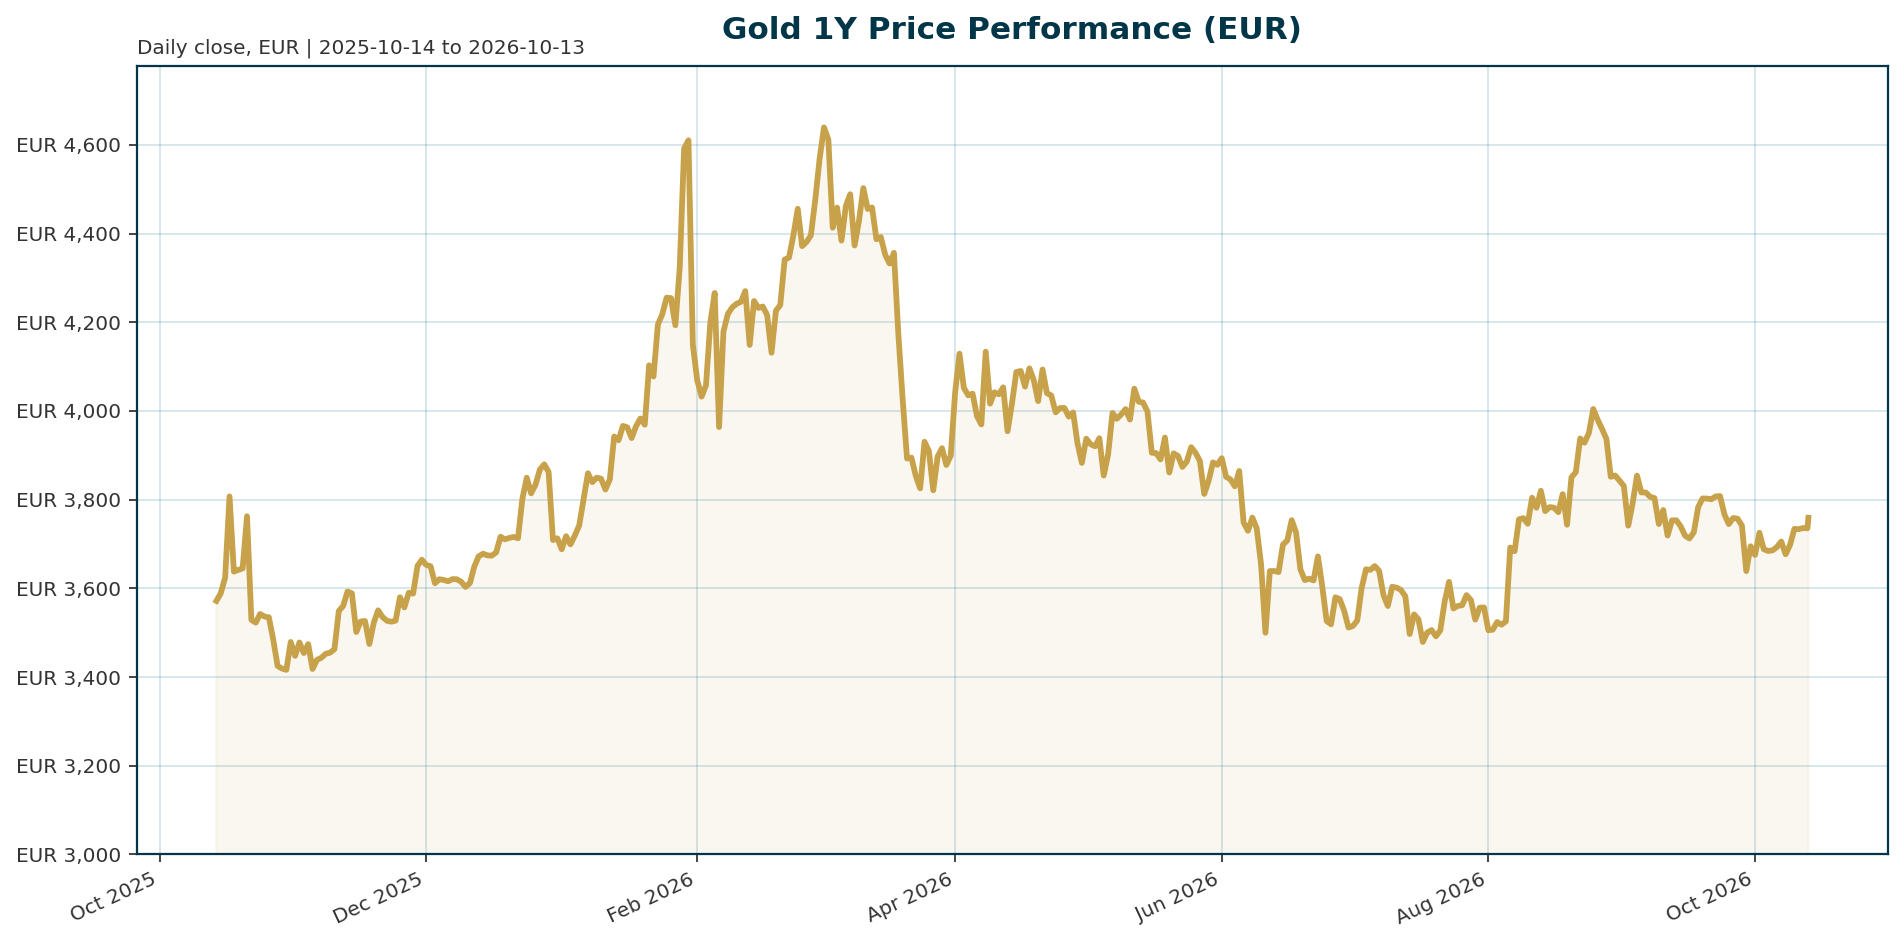
| 30d / 200d / 1y | -3.92% / -5.63% / +3.35% | Medium-term trend remains corrective, while 1-year return is still positive |
| 24h range | €3,715.28 to €3,751.52 | Range: €36.24, or 0.98% of the low. Data issue: spot is above the reported 24h high |
| All-time high | €4,688.32 on 2026-01-28 | Drawdown: (€3,753.23 / €4,688.32 – 1) x 100 = -19.94% |
| All-time low | €1,265.28 on 2019-11-17 | Gain: (€3,753.23 / €1,265.28 – 1) x 100 = +196.63% |
| 24h volume | €103.76m | Volume-to-market-cap: €103.76m / €1.649bn = 6.29% |
| Market cap | €1.649bn | Proxy-specific, not the global physical gold market |
| Circulating / total supply | 439,428.707863 / 439,428.707863 | FDV-to-market-cap: €1.649bn / €1.649bn = 1.00x |
| EUR/USD | 1.1200 | -0.14% over 5d, -3.52% over 1m, -4.68% YTD |
| Implied USD translation | €3,753.23 x 1.1200 = $4,203.62 | Translation estimate only, not a sourced USD spot quote |
XAU/EUR is firm on a 1-hour, 24-hour and 7-day basis, but the 30-day and 200-day declines argue against calling this a confirmed momentum breakout. The price sits materially below the January 2026 high, yet far above the 2019 low. For institutional EUR investors, this creates a balanced setup: gold remains a strategic hedge, but tactical upside requires confirmation from real-yield, reserve-demand or FX channels.
Macro Backdrop
The broad market backdrop is neutral-to-negative for risk sentiment. Equity momentum is mixed, DACH indicators are broadly in line with global peers, euro yields are mixed and FX is mixed. DACH indicators average -1.68% over 5 days versus -1.46% for global equity indicators. The Euro Area AAA 10-year yield is 3.51%, up 0.9 bp over 5 days, while the 10-year minus 2-year spread is 46.4 bp. EUR/USD is 1.1200, down 0.14% over 5 days. This backdrop supports gold primarily as a hedge and reserve asset, not as a simple risk-on instrument.
The gold-specific macro question is whether defensive demand can offset the opportunity cost of holding a non-yielding asset. Historically, gold tends to move inversely to real yields because it pays no coupon or dividend and competes with inflation-adjusted bond returns [T3]. The data bundle provides nominal euro yields, but inflation expectations and real-yield series are unavailable, so the real-yield discussion must remain qualitative.
The bullish macro case rests on three linked forces. First, if inflation proves sticky while nominal rates stop rising, real yields can fall and support gold. Second, fiscal uncertainty and policy-credibility concerns can increase demand for assets outside the sovereign-liability complex [T5]. Third, geopolitical fragmentation can affect supply chains, inflation, monetary policy risk balances and reserve management, increasing the institutional relevance of gold [T8].
The bearish macro case is also clear. Euro Area AAA yields are elevated in nominal terms: the 2-year yield is 3.0469% and the 10-year yield is 3.5112%. The 10-year minus 2-year calculation is (3.5112% – 3.0469%) x 100 = 46.4 bp. If inflation expectations decline faster than nominal yields, real yields can rise and pressure gold. In that regime, cash and high-quality bonds become more competitive.
Investment Thesis
Gold in EUR should be treated as a strategic diversifier with tactical sensitivity to real yields, inflation persistence, policy credibility, reserve diversification and EUR/USD. It is not a cash-flow asset. It has no coupon, dividend or earnings stream, so valuation must rely on macro regime, scarcity, flow support and FX translation rather than discounted cash flow.
The constructive thesis is that gold benefits when investors question the real value of fiat savings, the sustainability of fiscal paths or the credibility of policy institutions. Gold supply grows slowly and predictably, which supports its role as a scarce real asset when inflation or currency confidence becomes unstable [T6]. Central-bank reserve management strengthens this case because gold is not directly tied to one currency, government or issuer [T7].
Official-sector demand remains central. J.P. Morgan cites a survey in which a record 43% of 73 global monetary authorities expected their own gold reserves to increase over the next year [T3]. The same source links reserve accumulation to elevated geopolitical risks and, for some countries, a desire to reduce vulnerability to dollar sanctions [T3]. This demand channel can reduce gold’s dependence on Western ETF flows, although it does not eliminate cyclical downside risk.
For EUR-based investors, FX translation is a material part of the thesis. EUR/USD has fallen 3.52% over one month and 4.68% year-to-date. A weaker euro can lift XAU/EUR even if USD gold is flat. Conversely, euro strength can compress local-currency returns even when the global gold thesis remains intact.
Bullish Drivers
- Real-yield relief: Falling real yields lower the opportunity cost of holding gold, improving the relative appeal of a non-yielding asset [T3].
- Inflation persistence: If inflation remains elevated or volatile, gold can attract demand from investors seeking to protect real purchasing power [T6].
- Central-bank buying: Central-bank reserve demand can add structural support. WisdomTree notes reported net central-bank additions of 23 tonnes in a referenced period [T4].
- Reserve diversification: Gold’s lack of issuer risk makes it attractive when reserve managers seek diversification away from single-currency exposure [T7].
- Geopolitical fragmentation: A more fragmented global environment raises the value of resilience in reserve portfolios [T8].
- Fiscal and policy-credibility risk: Persistent fiscal uncertainty, public-debt concerns and declining confidence in some currencies can support gold demand [T5].
- EUR weakness: EUR/USD weakness of -3.52% over one month and -4.68% YTD can magnify XAU/EUR gains when USD gold is stable or rising.
The bullish case is credible but not unconditional. It requires either lower real yields, stronger reserve-flow evidence, renewed risk aversion, or further euro depreciation. Without these catalysts, gold may continue to consolidate below the January 2026 peak.
Relative Positioning vs Bitcoin and Ethereum
| Asset | Available data | Institutional interpretation |
|---|---|---|
| Gold / XAU in EUR | €3,753.23; +3.35% 1y; -3.92% 30d; -5.63% 200d | Macro hedge, real-yield-sensitive reserve asset |
| Bitcoin | Direct BTC price and return data unavailable; BTC dominance is 59.30% | Quantitative comparison unavailable from supplied data |
| Ethereum | Direct ETH price, market cap, volume and return data unavailable | Quantitative comparison unavailable from supplied data |
| Total crypto market | Market cap: $2.525tn; 24h volume: $85.98bn | Shows liquidity and scale, but not relative performance versus gold |
Gold’s role differs from Bitcoin and Ethereum. Gold has a long reserve-asset history and receives support from central-bank demand, inflation concerns and real-yield dynamics [T7]. Bitcoin and Ethereum may offer digital-scarcity and network-exposure narratives, but the supplied bundle does not include their prices, returns, volatility or correlations. As a result, any relative ranking would be qualitative rather than evidence-based.
In a neutral-to-negative risk backdrop, gold may be favoured by institutions seeking lower-beta portfolio hedges. In a renewed liquidity expansion, Bitcoin and Ethereum could outperform because of higher beta, but that cannot be demonstrated quantitatively with the current data. Direct BTC and ETH metrics are unavailable.
Scenario Framework
| Scenario | Macro conditions | XAU/EUR implication |
|---|---|---|
| Base case | Neutral-to-negative risk sentiment, mixed euro yields, moderate EUR weakness, continued reserve diversification | Gold consolidates below the €4,688.32 ATH. Strategic allocation remains justified, but upside is capped by elevated nominal yields. |
| Bull case | Real yields decline, inflation remains sticky, fiscal credibility weakens, geopolitical fragmentation persists and central banks keep adding gold | XAU/EUR retests the prior high. Required move: (€4,688.32 / €3,753.23 – 1) x 100 = +24.9%. |
| Bear case | Disinflation becomes credible, real yields rise, ETF demand weakens and physical demand softens | XAU/EUR extends the correction. The 30-day decline of -3.92% and 200-day decline of -5.63% become trend signals rather than noise. |
| EUR-upside case | EUR weakens further versus USD while USD gold is stable or higher | Local-currency returns improve through translation. A weaker EUR supports XAU/EUR independently of global gold fundamentals. |
| EUR-downside case | EUR rebounds sharply while USD gold is flat or falling | Translation becomes a headwind and can offset a stable global gold price. |
Lombard Odier argues that gold’s sensitivity to real yields has reasserted itself in recent months and that restrictive Federal Reserve policy could weigh on gold if it produces persistently higher real yields [T5]. The same source identifies higher-for-longer real yields, prolonged ETF outflows and weaker physical demand, including jewellery, as key risks [T5]. That keeps the scenario distribution balanced rather than one-sided.
Valuation Discussion
Gold cannot be valued like an equity or bond. It has no earnings, coupon or maturity value. The appropriate valuation frame is opportunity cost, inflation regime, reserve-flow support, scarcity and currency translation.
On a spot basis, XAU/EUR is below peak but not cheap in a long-cycle sense. The current price of €3,753.23 is 19.94% below the January 2026 ATH of €4,688.32. It is also 196.63% above the November 2019 ATL of €1,265.28. That combination argues for valuation discipline: the drawdown improves the entry point relative to the peak, but the asset remains substantially re-rated versus its prior cycle low.
The opportunity-cost channel is the most important valuation anchor. When real yields fall, gold’s lack of income becomes less punitive. When real yields rise, bonds and cash compete more effectively [T3]. The bundle provides nominal euro yields but no inflation-expectation series, so a precise real-yield valuation model is unavailable.
Reserve demand can shift valuation anchors. If central banks continue to accumulate gold for diversification, sanctions resilience or geopolitical reasons, gold may sustain a higher regime price than real-yield models alone would imply [T3]. The bearish offset is that private demand still matters. ETF demand data are unavailable in the bundle, while jewellery and physical-demand data are also unavailable.
For EUR investors, fair value also depends on EUR/USD. At EUR/USD 1.1200, the implied USD translation is approximately $4,203.62 per ounce equivalent. If the euro strengthens, XAU/EUR can fall even if USD gold is stable. If the euro weakens further, XAU/EUR can rise without a change in global gold fundamentals.
Risks
- Real-yield risk: Higher-for-longer real yields increase the opportunity cost of holding gold and remain the main macro downside risk [T5].
- Policy risk: More restrictive monetary policy can weigh on gold if it produces persistently higher real yields [T5].
- Flow risk: A prolonged decline in ETF demand would reduce private-sector support [T5]. ETF-flow data are unavailable in the bundle.
- Physical-demand risk: Lower jewellery or broader physical demand can weaken the market even if central banks keep buying [T5]. Physical-demand data are unavailable.
- FX risk: EUR appreciation versus USD would reduce XAU/EUR returns for local investors, all else equal.
- Trend risk: XAU/EUR is positive over 24 hours and 7 days, but negative over 30 days and 200 days. Medium-term momentum remains fragile.
- Data-quality risk: The reported 24h high of €3,751.52 is below the current price of €3,753.23. This inconsistency should be verified before trade execution.
- Proxy risk: Market cap, rank, volume and supply appear linked to a tokenized gold proxy, not the full physical gold market.
- Relative-asset risk: Direct Bitcoin and Ethereum price, return, volatility and correlation data are unavailable, limiting comparative allocation conclusions.
Appendix
Methodology and Data Notes
- Asset: Gold, symbol XAU, quote currency EUR.
- Report generated at 2026-10-13 04:53:58 UTC.
- Market data retrieved at 2026-10-13 04:53:47 UTC.
- Market overview data were retrieved between 2026-10-13 04:53:52 UTC and 2026-10-13 04:53:58 UTC, depending on data point.
- The market-data coingecko_id is pax-gold. Market cap, circulating supply, fully diluted valuation, rank and volume should be treated as tokenized-gold proxy metrics unless independently verified.
- The market overview module reported no errors.
- Real-yield data, inflation expectations, ETF flows, central-bank reserve-flow time series, jewellery demand, direct Bitcoin price data and direct Ethereum price data are unavailable in the supplied bundle.
Calculation Definitions
- ATH drawdown: (€3,753.23 / €4,688.32 – 1) x 100 = -19.94%.
- ATL gain: (€3,753.23 / €1,265.28 – 1) x 100 = +196.63%.
- 24h range: €3,751.52 – €3,715.28 = €36.24. Range as a percentage of low: €36.24 / €3,715.28 x 100 = 0.98%.
- Implied USD translation: €3,753.23 x 1.1200 = $4,203.62.
- Euro Area AAA 10Y-2Y spread: (3.5112% – 3.0469%) x 100 = 46.4 bp.
- Volume-to-market-cap: €103.76m / €1.649bn = 6.29%.
- FDV-to-market-cap: €1.649bn / €1.649bn = 1.00x.
Sources
- [T3] Is it a golden era for gold? | J.P. Morgan Private Bank U.S.
- [T4] WisdomTree Gold Monthly | NL
- [T5] Gold’s slowdown doesn’t signal a reversal | Lombard Odier
- [T6] How Inflation and Interest Rates Affect Gold Prices in 2026
- [T7] What Affects Gold Prices? 6 Key Factors Explained | XTB
- [T8] Shifting ground: how geopolitics is reshaping growth, monetary policy and the role of gold as a reserve asset | Bank for International Settlements
This report is AI-generated, for informational purposes only, and does not constitute investment advice, a recommendation, an offer, or a solicitation to buy or sell any financial instrument.
Important Note / Wichtiger Hinweis:
EN: This report may have been generated using AI. It processes data from publicly available sources. The content is provided for informational purposes only.DE: Dieser Bericht kann mithilfe von KI erstellt worden sein. Dabei werden Daten aus öffentlich zugänglichen Quellen verarbeitet. Die Inhalte dienen ausschließlich Informationszwecken.
* DE: Die ergänzenden Inhalte können KI-generiert sein. EN: The additional content may be AI-generated.