Watch the video
This player shows only the Gold chapter of the daily altii market briefing. Watch the full video on tube.altii.de.
Key Data Snapshot
| Metric | Value |
|---|---|
| Price (EUR) | 3,713.11 |
| 24h Change | +0.38% |
| 30d Change | -4.44% |
| 200d Change | -10.77% |
| All-Time High (ATH) | 4,688.32 EUR (Jan 28, 2026) |
| Market Cap | 1.64B EUR |
| 24h Volume | 74.16M EUR |
| BTC Dominance | 60.13% |
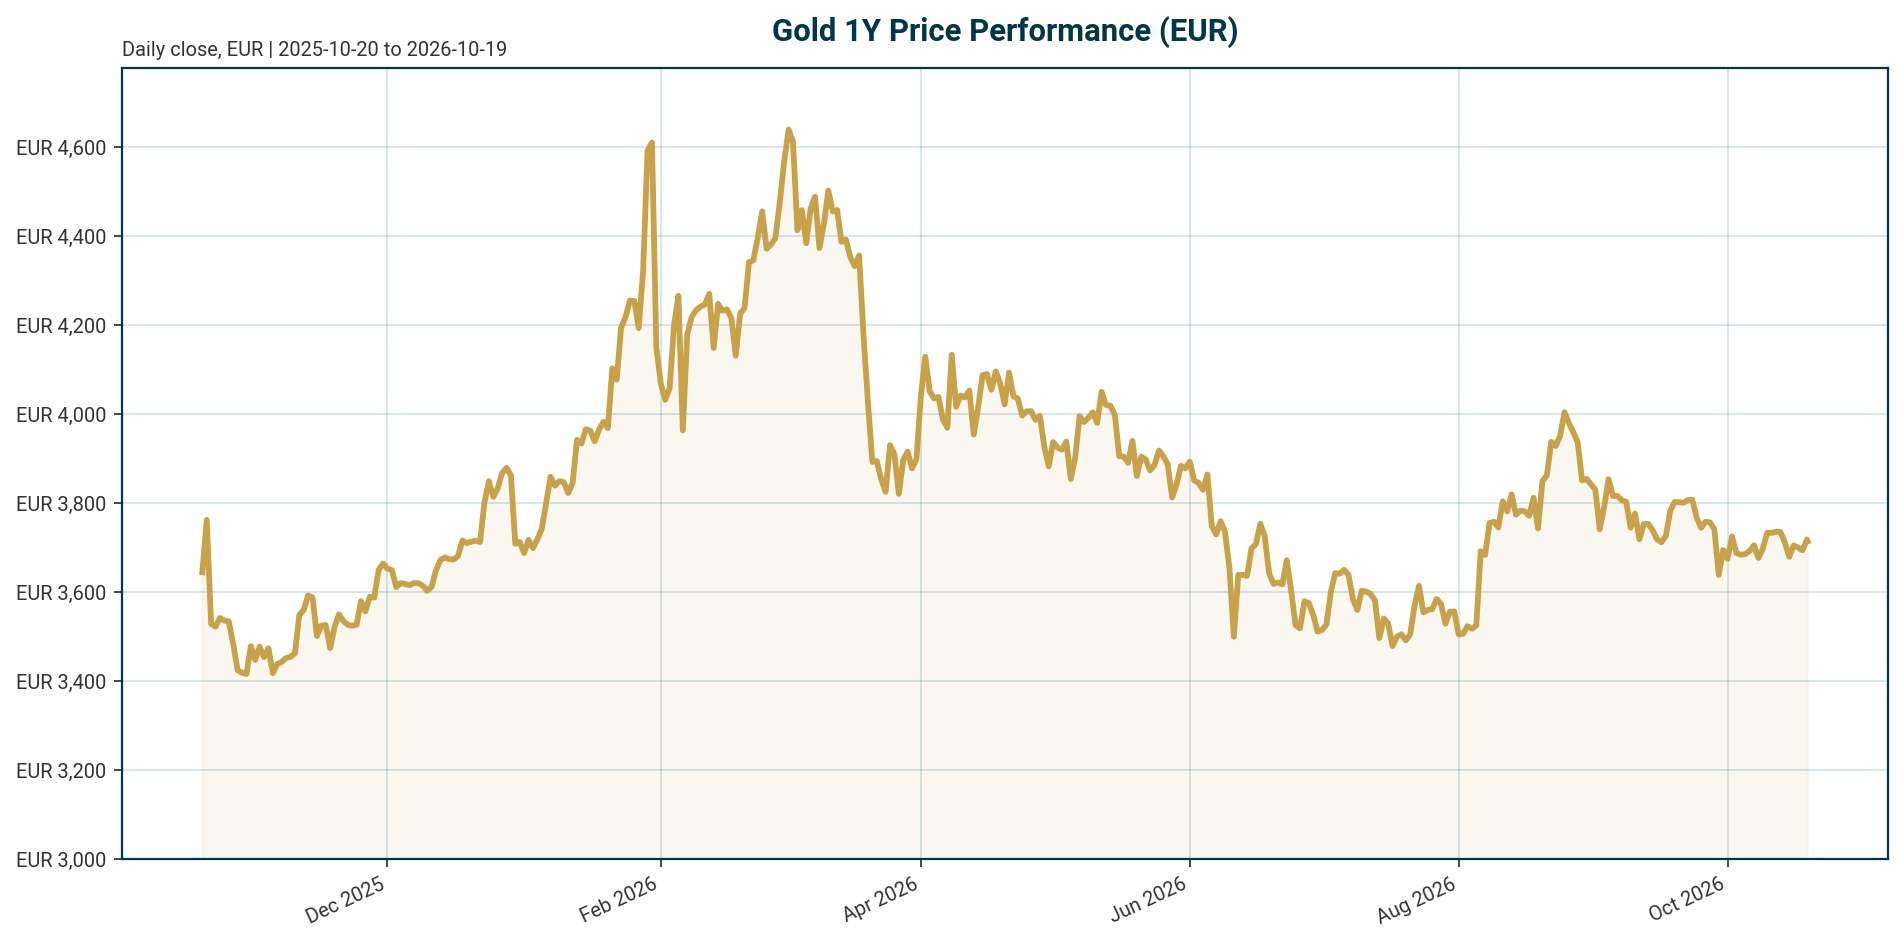
Gold has stabilized after a significant drawdown from its January 2026 ATH. The current price of 3,713.11 EUR reflects a -10.77% correction over the past 200 days, yet the asset remains above the 3,600 level. Despite a positive 24-hour move (+0.38%), the 30-day trend remains negative, indicating ongoing profit-taking from recent highs.
Macro Backdrop
Risk sentiment is neutral to negative, characterized by divergent equity performance and a flattening yield curve in the Euro area. The DAX leads regional equities with a strong 5-day gain of 1.36%, while the Nikkei 225 underperforms with a 5-day decline of -4.81% [market_overview]. The Euro area AAA 10-year yield sits at 3.39%, with the 10Y-2Y spread narrowing to 39.8 bp, signaling a flattening curve [market_overview].
Monetary policy remains restrictive but data-dependent. The Federal Reserve has maintained its upper bound at 3.75%, while the Consumer Price Index runs at the 91st percentile of its 12-month range, suggesting sticky inflation [T1]. Real yields on 10-year TIPS hover around 2%, a level historically conducive to gold accumulation despite the headwind of elevated nominal rates [T1].
Investment Thesis
The primary thesis for Gold (XAU) centers on a structural shift in demand dynamics. Despite persistently positive real yields, gold has broken away from historical correlation models that typically limit upside when rates rise [T2]. The market is undergoing a “re-anchoring” of pricing logic, where structural factors—specifically central bank accumulation and geopolitical risk—provide a higher floor for prices [T3].
Investors are increasingly viewing gold as a hedge against sovereign debt sustainability and currency debasement rather than a simple rate play. As public debt-to-GDP ratios in advanced economies approach post-war highs, the case for gold as a reserve asset strengthens, offering insulation against financial repression and inflation [T5].
Bullish Drivers
- Central Bank Accumulation: The World Gold Council reports that central banks have averaged 1,000 tonnes of gold purchases over the past four years, a significant acceleration from the 500-tonne average of the preceding decade [T7]. A record 43% of 73 global monetary authorities plan to increase their gold reserves over the next year, driven by geopolitical risks and a desire to reduce dollar exposure [T8].
- Geopolitical & Energy Risks: Persistent geopolitical tensions, including the US-Iran conflict, have pushed oil prices above $100, reinforcing inflationary pressures [T3]. Central banks are actively adjusting storage locations for crisis preparedness, such as the Dutch Central Bank moving 86 tonnes of gold from the US and Canada to London [T3].
- Reserve Diversification: The share of gold in global central bank reserves has risen from roughly 14% in 2023 to nearly 25% [T3]. This trend reflects a strategic pivot toward dedollarization and a recognition of gold’s role as a non-sovereign reserve asset [T5].
Relative Positioning vs Bitcoin and Ethereum
Gold maintains its status as the dominant store of value with a BTC dominance of 60.13% [market_data]. While Bitcoin and Ethereum continue to attract speculative capital, gold is increasingly viewed as the primary hedge against systemic monetary policy risks [T8]. Unlike digital assets, which are highly sensitive to risk-on sentiment, gold’s correlation with traditional bond yields has weakened, allowing it to perform independently of equity market volatility [T3].
Scenario Framework
- Base Case (Consolidation): Real yields remain range-bound between 2% and 3%. Central banks continue steady accumulation. Gold consolidates between 3,800 and 4,200 EUR.
- Bullish Case: The Federal Reserve and ECB pivot to neutral rates, causing real yields to fall below 1.5%. Structural demand from central banks accelerates. Price target exceeds 4,500 EUR.
- Bearish Case: A significant inflation shock forces central banks to raise rates, pushing real yields above 3.5%. Profit-taking accelerates. Price tests support levels below 3,200 EUR.
Valuation Discussion
Current valuations appear justified by the “debasement trade” and structural demand, rather than traditional yield sensitivity. Société Générale notes that while real yields are high, gold has continued to trade near record highs, breaking away from historical models that would imply lower prices [T2]. The structural demand from central banks has effectively capped the downside risk, creating a new valuation floor [T2].
Risks
- Real Yield Spike: A resurgence in inflation could force central banks to maintain restrictive policy, keeping real yields elevated and posing a headwind for gold [T4].
- Profit Taking: Gold is up roughly 6% year-to-date, leaving the market vulnerable to bouts of profit-taking, particularly if short-term momentum traders exit positions [T4].
- Geopolitical Resolution: If geopolitical tensions de-escalate and energy prices stabilize, the immediate safe-haven demand for gold could diminish [T4].
Appendix
Sources
- Central Banks Are Snapping Up Gold, ETF Investors Are Just Waking Up: The Best Gold ETFs to Own Before It Hits $5,000 – 24/7 Wall St. [T1]
- It’s time to get bullish on gold again, says SocGen | Kitco News [T2]
- Gold Holds Above $4,000 Even as US Treasury Yields Top 5% — Institutions Say Gold’s Pricing Logic Is “Re-Anchoring” — BigGo Finance [T3]
- Geopolitics alone isn’t enough to lift gold | articles | ING THINK [T4]
- Report: Central Banks Now Hold More Gold Than Treasuries—What That Means for Global Capital and Currencies – CEOWORLD magazine [T5]
- How Geopolitics Is Reshaping Growth, Monetary Policy … | Bundesbank [T6]
- Central Bank Gold Purchases Hit 1,000t Average: WGC Survey [T7]
- Is it a golden era for gold? | J.P. Morgan Private Bank U.S. [T8]
This report is AI-generated, for informational purposes only, and not investment advice. The analysis is based on data available as of October 19, 2026.
Important Note / Wichtiger Hinweis:
EN: This report may have been generated using AI. It processes data from publicly available sources. The content is provided for informational purposes only.DE: Dieser Bericht kann mithilfe von KI erstellt worden sein. Dabei werden Daten aus öffentlich zugänglichen Quellen verarbeitet. Die Inhalte dienen ausschließlich Informationszwecken.
* DE: Die ergänzenden Inhalte können KI-generiert sein. EN: The additional content may be AI-generated.